



By AI-Powered PMC Akbar Jiwani, Special Correspondent – Real Estate, Realnewsofindia.com
India’s residential real estate market showed resilience rather than retreat in the second quarter of 2026, with the country’s top eight cities recording 91,729 home sales even as headline numbers dipped from a year ago, according to the latest quarterly market reports. The data paints a picture of a sector settling into a more mature, selective phase of growth rather than one in decline — a distinction industry watchers say matters for homebuyers, developers and policymakers alike.
THE HEADLINE NUMBERS
Across the eight major markets — Mumbai Metropolitan Region (MMR), Bengaluru, Pune, Hyderabad, Chennai, Delhi-NCR, Kolkata and Ahmedabad — developers sold 91,729 units in Q2 2026, a sequential dip of 4.4 percent and a year-on-year decline of 6.1 percent from 97,674 units in the same quarter last year. New launches followed a similar pattern, with 89,161 units introduced during the quarter, down 4.2 percent quarter-on-quarter but still up 6.0 percent compared to a year earlier.
The average sales-weighted price across these markets rose to Rs 10,153 per square foot, a modest 1.0 percent increase over the previous quarter — evidence that even as unit sales softened, pricing power held firm in most micro-markets.
A CITY-BY-CITY PICTURE
The national numbers mask sharply divergent stories at the city level.
Hyderabad was the standout performer, with home sales rising 14.6 percent year-on-year to 13,196 units, supported by a 21.6 percent jump in new launches — a sign that developers remain confident in the city’s demand fundamentals.
Chennai posted the sharpest sales growth of any major market, up 36 percent year-on-year to 7,183 units, even as new launches there fell 43.3 percent annually, pointing to pent-up demand being absorbed against constrained new supply. Prices in the city rose 4.4 percent.
The Mumbai Metropolitan Region remained the country’s largest market by volume, with 24,112 units sold, though this was down 7.0 percent year-on-year. MMR also commanded the highest average price among the eight cities at Rs 15,422 per square foot, up a striking 20.4 percent from a year ago — underscoring how affordability pressures are building even as absolute sales cool.
Bengaluru and Pune, both closely tied to the technology sector, saw sales decline 9.2 percent and 20.8 percent year-on-year respectively. Bengaluru’s average price nonetheless climbed 26 percent annually to Rs 9,931 per square foot, while Pune crossed the Rs 8,000 per square foot mark for the first time in its history, at Rs 8,084.
Delhi-NCR and Ahmedabad both saw sales fall roughly 7-20 percent year-on-year, though Ahmedabad recorded the strongest quarter-on-quarter price gain of any city at 7 percent, while remaining the most affordable major market at Rs 5,295 per square foot. Kolkata’s sales dipped 8.6 percent annually but rose 22 percent sequentially — the strongest quarter-on-quarter recovery among the eight cities.
WHAT’S DRIVING THE SLOWDOWN — AND THE RESILIENCE
Analysts point to a mix of global and sector-specific headwinds behind the softer sales numbers, particularly in technology-heavy cities such as Bengaluru and Pune. AI-led workforce restructuring across the IT and technology sector has weighed on buyer sentiment and hiring-linked home purchases, while broader global uncertainty — including the fallout from the US-Iran conflict — has added caution to big-ticket discretionary spending in tech hubs.
Yet the market has had genuine tailwinds to lean on. The Reserve Bank of India has kept its repo rate steady at 5.25 percent, providing predictability on home-loan interest rates at a time when affordability is already stretched in top-tier markets. Meanwhile, recent GST rationalisation on key construction materials has offered developers some relief on input costs, support that should filter through to project viability and, over time, to pricing.
Industry voices have been quick to frame the quarter as one of maturation rather than weakness. As one developer executive summarised: “Q2 2026 confirms India’s residential market is maturing, not weakening. Prices held above Rs 10,000 per square foot despite selective buying.”
THE GOVERNMENT’S PARALLEL PUSH ON STALLED HOUSING
The quarter’s sales data arrives alongside continued government efforts to address one of Indian real estate’s most persistent problems: stalled housing projects. The Special Window for Affordable and Mid-Income Housing Investment Fund (SWAMIH), launched in 2019 and managed by SBICAP Ventures, has now completed more than 58,000 homes across 146 projects in 20 cities and 12 states, unlocking over Rs 49,500 crore in capital and creating more than 30,000 jobs in the process. The fund is on track to deliver over 1 lakh homes in total, benefiting an estimated 2.38 lakh people.
Building on that track record, the Union Budget for 2025-26 announced SWAMIH Fund 2, a new Rs 15,000 crore blended-finance vehicle backed by the government, public sector banks and LIC, aimed at completing a further 1 lakh stalled units. Together with steady interest rates and GST relief on construction inputs, the SWAMIH initiative forms a key plank of the government’s strategy to keep housing delivery on track even as headline sales volumes moderate.
THE OUTLOOK
Taken together, the Q2 2026 numbers suggest an Indian housing market that is recalibrating rather than reversing course: sales are down from last year’s highs, but prices are largely holding or rising, government-backed liquidity support for stalled projects continues to scale up, and pockets of strong demand — Hyderabad and Chennai chief among them — point to underlying confidence that remains intact. For homebuyers and investors watching the market, the message from this quarter is one of selective opportunity rather than either euphoria or alarm.

By AI-Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
New Delhi, August 21, 2026 — India’s senior living housing segment is emerging as one of the fastest-growing niches within the country’s real estate sector, with developers, operators and private equity investors committing more than Rs 13,000 crore since January 2025 toward new projects, according to industry data reviewed this week. The wave of capital is expected to add roughly 75,000 new senior living units to the market over the next three to four years, more than tripling the current organised inventory of around 25,000 units.
The investment surge comes as India’s elderly population continues to expand rapidly and urban families increasingly seek professionally managed, lifestyle-oriented housing for ageing parents rather than relying solely on traditional joint-family arrangements.
A MARKET ON THE VERGE OF A TRILLION-RUPEE MILESTONE
According to research from property consultancy Colliers India, the organised senior living market — currently valued at roughly Rs 30,000 crore — is projected to nearly quadruple to about Rs 1 lakh crore by 2030. The consultancy expects the segment to grow from Rs 30,000 crore to nearly Rs 70,000 crore by 2028 en route to that milestone, with organised inventory rising from 25,000 units today to as many as 1 lakh units by the end of the decade.
Even so, supply remains well short of underlying need. Colliers estimates demand for senior housing could reach 28-30 lakh units by 2030, up from 20-22 lakh units currently, meaning the organised, professionally managed segment still covers only a sliver of the total market — penetration is expected to rise from about 1.3 percent today to roughly 4 percent by 2030.
“India’s senior living market is entering a period of accelerated growth, driven by strong demographic shifts,” said Badal Yagnik, CEO of Colliers India. “Organised senior living inventory is expected to quadruple over the next three to four years and become a trillion-rupee market by 2030.”
BEYOND METROS: TIER II, III CITIES AND SPIRITUAL HUBS LEAD EXPANSION
Unlike earlier waves of real estate investment concentrated in India’s largest metropolitan markets, the senior living boom is notably decentralised. Industry estimates suggest 30-40 percent of new senior living launches over the coming years will be located in Tier II and Tier III cities and pilgrimage destinations, including Coimbatore, Puducherry, Dehradun and Vadodara, as well as spiritual hubs such as Tirupati, Vrindavan and Ayodhya.
Developers active in the space say the shift reflects both land economics and a change in how Indian families view senior housing.
“Senior housing is emerging as a preferred lifestyle choice for seniors who value independence, community living and access to quality healthcare, rather than a last-resort option,” said Anil Godara of Gurugram-based J Estates, one of the developers expanding in the segment.
Adarsh Narahari of Primus Senior Living echoed the sentiment, noting a broader generational shift: “People are living longer, families are more spread out geographically, and there is a real conversation now about what a good old age actually looks like — that is driving demand for purpose-built communities.”
TECHNOLOGY AND HEALTHCARE INTEGRATION RESHAPING THE PRODUCT
New-generation senior living projects are increasingly bundling real estate with healthcare infrastructure, industry data shows. Developers are integrating telemedicine access, remote health monitoring and AI-enabled emergency response systems into project design, positioning senior living as a hybrid of residential real estate and managed healthcare services rather than standalone housing stock.
This convergence has attracted institutional investors and private equity players who see recurring, service-linked revenue streams — such as facility management, healthcare tie-ups and hospitality services — layered on top of traditional real estate returns, a model that has already proven successful in more mature senior housing markets overseas.
WHAT IT MEANS FOR INDIA’S BROADER REAL ESTATE GROWTH STORY
The senior living surge fits into a wider pattern of resilience across Indian real estate this year. Separately, industry data released this week showed India’s real estate sector attracted robust capital inflows in the first half of 2026 even amid global geopolitical headwinds, underscoring continued investor confidence in the country’s property fundamentals — from housing and office space to specialised segments like senior living, data centres and warehousing.
For India’s rapidly ageing demographic — and for a real estate industry looking for its next high-growth vertical — the senior living segment is fast becoming a bellwether. With committed capital already exceeding Rs 13,000 crore and mainstream developers entering what was once a niche category, the sector is on track to become a defining growth story for Indian real estate through the end of the decade.
—
By AI-Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
NEW DELHI, August 20, 2026 — India’s real estate sector has received a significant regulatory cushion this month, with the Ministry of Housing and Urban Affairs directing Real Estate Regulatory Authorities (RERAs) across states to grant eligible housing projects a blanket extension of up to four months on their completion timelines. The move comes as the industry grapples with supply-chain disruptions triggered by the ongoing West Asia conflict, and it marks one of the most consequential government interventions in the sector this year.
A “Force Majeure” Call from the Centre
The Department of Expenditure has formally classified the West Asia crisis as a “force majeure” event, citing disrupted global supply chains, sharply higher freight costs, and shortages of key construction inputs — cement, steel, aluminium and copper — that have hit builders nationwide. Acting on this classification, the housing ministry has advised state RERAs to extend timelines for projects whose original or previously extended completion date falls on or after February 28, 2026. Developers can apply for the extension through a single, simplified application, without additional paperwork or scrutiny of individual project delays.
Haryana RERA has already acted on the advisory, granting the four-month extension to all its registered projects, following an identical move by Maharashtra RERA. Industry voices from the National Capital Region — including Signature Global’s Pradeep Aggarwal, SS Group’s Ashok Singh Jaunapuria, and Ganga Realty’s Neeraj K Mishra — have welcomed the relief, noting that construction costs have risen an estimated 15–30 percent and labour costs 15–20 percent since February 2026, driven by higher prices for steel, cement, aluminium, fuel and imported materials.
What It Means for Homebuyers
For prospective homeowners, the extension translates into a real, if unwelcome, shift in expectations: possession dates for a large number of under-construction projects are likely to move by up to four months. Property consultancy Anarock estimates that roughly 54 lakh homes across the country could see delivery pushed back this year as a result of the disruption. Buyers who had planned relocations, house-warming ceremonies, or loan-linked possession milestones around earlier dates will need to revise those plans.
Importantly, legal experts have cautioned that the force majeure extension is meant to cover timelines alone — it does not entitle developers to raise prices on units already sold, unless the original buyer agreement explicitly permits cost escalation clauses. RERA authorities have signalled they will continue to scrutinise complaints closely: Kerala RERA, for instance, recently ordered a builder to pay 16.65 percent simple annual interest over seven years for delays it ruled were not genuinely justified, rejecting the developer’s citing of demonetisation, floods and the pandemic as excuses. Homebuyers who believe a developer is misusing the extension can still file complaints online with supporting documentation, and RERA’s existing remedies — compensation, interest payments, refunds and possession orders — remain fully in force.
A Sector Holding Its Ground
The regulatory relief lands alongside broader signs of resilience in India’s property market. A fresh assessment from CareEdge Ratings this week found that the domestic real estate sector is likely to stay resilient despite the West Asia crisis, pointing to healthy underlying housing demand and steady capital inflows into Indian real estate even as global uncertainty persists. Taken together, the RERA extension and the ratings agency’s outlook suggest that while builders are absorbing real cost pressure, the sector’s fundamentals — demand, investor appetite, and regulatory support — remain intact heading into the second half of 2026.
For an industry that has spent the past several years rebuilding buyer trust under the RERA framework, this latest intervention is being read as evidence that the regulatory system can flex to protect legitimate developers from external shocks, while still holding the line against those using the crisis as cover for undue delay.
—
Written by AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
New Delhi, August 19, 2026
The Delhi Development Authority (DDA) has cleared the Master Plan for Delhi 2047 (MPD-2047), setting the stage for the most significant reset of the capital’s urban and real estate landscape in over two decades. The plan, approved on August 12 under Lieutenant Governor Taranjit Singh Sandhu, now moves to the Union Ministry of Housing and Urban Affairs (MoHUA) for final approval and official notification — a step developers, homebuyers and investors across the National Capital Region are watching closely.
A Plan Five Years in the Making
MPD-2047 is only the fourth master plan in Delhi’s history, following the original 1962 plan and subsequent iterations in 2001 and 2021. Notably, the DDA had first cleared a draft as far back as February 2023, but the plan faced repeated delays before finally clearing this month. Its extended horizon — through 2047 — deliberately aligns with the central government’s “Viksit Bharat 2047” vision of a developed India by the centenary of independence.
What Changes for Housing
The plan’s most consequential move for the housing market is a uniform redevelopment policy for Delhi’s ageing two-storey residential colonies, many of which are more than 50 years old and structurally deficient. Under the new framework, built-up two-storey units will now receive redevelopment rights equivalent to vacant residential plots — potentially unlocking large-scale reconstruction across DDA-built housing stock that has long been considered undevelopable under existing rules.
The plan also leans heavily on Transit-Oriented Development (TOD), permitting higher-density construction along metro and rail corridors, alongside eased land-pooling norms intended to unlock fresh land parcels for housing. The urgency behind this push is stark: data cited alongside the plan shows affordable homes priced under ₹40 lakh made up 62 percent of new launches in Delhi-NCR in 2020, but had collapsed to just 11 percent of supply by 2025, even as luxury units swelled to roughly 70 percent of new launches. Officials are framing TOD and land-pooling reforms as a direct answer to that affordability squeeze.
Yamuna Floodplain Gets Protection
In a significant environmental commitment, MPD-2047 imposes a ban on concrete construction in the core Yamuna floodplain, designated the O-Zone — an attempt to permanently shield the river’s ecosystem from further encroachment after years of contested development pressure along its banks.
Regularisation and Ease of Approvals
The plan also proposes regularising 1,511 unauthorised colonies on an “as-is-where-is” basis, a move that could bring long-pending legal clarity to lakhs of residents living in such settlements. Separately, amendments to the Unified Building Bye-Laws are intended to simplify and speed up building permit approvals — a persistent grievance among both individual homeowners and developers navigating Delhi’s construction clearance process.
The Investment Number Everyone Is Talking About
Industry estimates accompanying the plan peg its potential to attract ₹25–30 lakh crore in investment over its lifecycle, spanning housing, commercial development, infrastructure and urban regeneration. The DDA has described the plan as adopting “an integrated approach towards housing, economic growth, mobility, environmental sustainability, infrastructure, heritage conservation, urban regeneration and citizen-centric governance.”
What Happens Next
MPD-2047 is not yet law. The plan now awaits final vetting and notification by MoHUA before it takes legal effect — a process that, given the plan’s own history of delay, developers are watching warily. Once notified, implementation will fall to the DDA and Delhi’s municipal bodies, with redevelopment and TOD provisions expected to be rolled out in phases rather than all at once.
Why It Matters
For homebuyers, the redevelopment policy could eventually widen supply in central and established Delhi neighbourhoods where new construction has been all but frozen for years. For developers, eased land pooling and TOD densification open fresh avenues in a market that has increasingly tilted toward premium and luxury launches at the expense of affordable stock. For the city at large, the Yamuna floodplain protections and colony regularisation address two of Delhi’s longest-running urban fault lines in a single stroke.
Whether MPD-2047 lives up to its ambition will depend on how quickly — and how faithfully — MoHUA notifies it and the DDA executes it. Realnewsofindia.com will continue tracking the plan’s progress through central government approval and its early implementation.
————————————————–
This article was researched and written by AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com, based on official DDA statements and reporting from Business Standard and Business Today.
y AI Powered PMC Akbar Jiwani, Special Correspondent — Real Estate, for Realnewsofindia.com
The Reserve Bank of India’s Monetary Policy Committee (MPC) has kept the repo rate unchanged at 5.25 percent for the fourth consecutive review, a decision announced by RBI Governor Sanjay Malhotra following the Committee’s three-day meeting held August 3–5, 2026. The central bank retained its “neutral” policy stance, signalling that it will continue to watch domestic inflation trends and global economic developments before making any further move on interest rates.
For India’s real estate sector, which has increasingly come to treat monetary policy announcements as a bellwether for demand, the decision lands as welcome, if unspectacular, news: stability rather than stimulus, but stability that developers and homebuyers alike say they can plan around.
What the Rate Hold Means for Homebuyers
Because the bulk of floating-rate home loans in India are now linked to the repo rate through external benchmark lending rates (EBLR), an unchanged repo rate translates directly into unchanged home loan EMIs. Borrowers with existing floating-rate loans will see no immediate change in their monthly outgo, while prospective buyers gain a rare commodity in today’s market: predictability.
That predictability matters. With India’s GDP growth for the year projected at around 6.7 percent, real estate advisors say the combination of steady borrowing costs and continued economic momentum should keep housing demand resilient across major micro-markets, particularly in the mid-income and premium segments.
Industry Reaction: Cautious Optimism
Reaction from developers and industry bodies has been consistently positive, framing the pause as a stabiliser for a sector that depends heavily on buyer confidence and financing certainty.
Kamlesh Thakur, President of NAREDCO Maharashtra, called the decision “a prudent approach amid global uncertainties,” adding that he expects housing demand to stay strong in both the mid-income and premium categories through the rest of the fiscal year.
Kaushal Agarwal, Chairman of The Guardians Real Estate Advisory, said the continuity in policy rates gives buyers “greater predictability,” and that with GDP growth holding near 6.7 percent, demand should remain robust across the country’s major cities.
Bhavesh Kothari, Founder and CEO of Property First Realty, echoed that sentiment: “A stable interest rate environment gives greater confidence to both buyers and developers, while supporting the housing sector’s long-term growth.”
Manan Joshi, Founder of Sarvam Properties, said a steady policy environment “helps maintain affordability and reinforces buyer confidence, particularly in emerging residential markets,” while Jash Panchamia, Executive Director of Jaypee Infratech Limited, noted that stable rates combined with healthy financing options should “sustain demand, particularly in mid-income housing.”
Not every voice was unreserved. Shraddha Kedia-Agarwal, Director at Transcon Developers, acknowledged that a rate cut would have offered a more direct affordability boost, but said the unchanged rate still “reassures consumers during economic uncertainty” and supports continued momentum in the premium and luxury segments. Shilpin Tater, Managing Director of Superb Realty, described the decision as balanced — giving developers room to plan with certainty while shielding homebuyers from any immediate uptick in lending rates.
Reading the Wider Policy Signal
The RBI’s fourth consecutive pause comes against a backdrop of broader regulatory activity in the housing sector this year. Real estate market trackers note that 2026 has been marked by tighter RERA compliance enforcement and a sharper focus on grievance redress mechanisms, reflecting a wider government push toward stronger developer accountability and buyer protection — themes that regulators and industry bodies alike have flagged as central to sustaining trust in the sector.
Taken together, a steady interest rate regime and continued regulatory tightening point to a real estate market that policymakers are trying to grow on a foundation of predictability rather than short-term stimulus. For a sector that has weathered volatile rate cycles in the past, that combination — even without a rate cut — is being read by most industry watchers as a net positive for sustained, healthier growth through the remainder of FY27.
By AI-Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
August 16, 2026
India’s real estate sector continues its steady climb through the third quarter of 2026, buoyed by stable interest rates, strong developer presales, and a landmark regulatory relief for homebuyers. Here is today’s roundup of the biggest stories shaping the country’s property market.
RBI HOLDS REPO RATE STEADY AT 5.25%, EMIS TO STAY UNCHANGED
The Reserve Bank of India’s Monetary Policy Committee has kept the repo rate unchanged at 5.25% for a fourth consecutive review, maintaining a neutral stance. The pause brings continued relief to homebuyers and developers alike, keeping home loan EMIs stable and supporting sustained demand in the housing market at a time when several metros are seeing renewed buyer activity.
NCR RESIDENTIAL PRICES JUMP 13% YOY AS NEW LAUNCHES SHRINK
Delhi-NCR has emerged as the fastest-appreciating residential market among India’s seven major metros, with prices rising approximately 13% year-on-year in the latest quarter. Gurugram’s key corridors — Dwarka Expressway, Southern Peripheral Road and Golf Course Extension Road — led the charge. New housing launches in the region fell roughly 40% year-on-year, and tight supply is keeping price momentum firm even as raw transaction volumes soften slightly. Analysts note that despite the price rise, affordability has actually improved for the first time since the post-pandemic surge, thanks to rising incomes and steady loan rates.
NOIDA OVERTAKES BENGALURU AND GURUGRAM IN PRICE GROWTH, POWERED BY JEWAR AIRPORT
Noida has recorded the sharpest residential price appreciation among major Indian cities, with average prices climbing roughly 111% between 2020 and 2025 — from about Rs 6,300 to Rs 13,300 per square foot — outpacing Gurugram’s 86% and Bengaluru’s 66% growth over the same period. The rally is being driven by the under-construction Noida International Airport at Jewar, expanding metro connectivity, new expressways, and a growing base of IT and manufacturing jobs pulling end-users (not just investors) into the market.
In a related development, the Yamuna Expressway Industrial Development Authority (YEIDA) has launched 973 residential plots across Sectors 15C, 18 and 24A near the upcoming airport, priced at approximately Rs 36,260 per square metre and allotted through a transparent, draw-based scheme.
LISTED DEVELOPERS POST STRONG Q1 FY27 PRESALES; GODREJ EXPANDS THANE LAND BANK
Leading listed developers — DLF, Lodha, Prestige, Oberoi Realty and Godrej Properties — reported robust presales growth for the June quarter, with the broader sector recording an estimated $2.3 billion in transaction volume. Godrej Properties also acquired an 18-acre land parcel in Thane with significant development potential, while several developers continued strategic land acquisitions along the Gurugram corridor, underscoring continued confidence in India’s residential growth story.
RERA DECRIMINALISATION: RELIEF FOR HOMEBUYERS, ACCOUNTABILITY INTACT FOR DEVELOPERS
In a significant regulatory shift, the Jan Vishwas (Amendment of Provisions) Act, 2026 has amended Section 68 of the Real Estate (Regulation and Development) Act, removing the threat of criminal imprisonment for homebuyers who fail to comply with tribunal orders. Previously, non-compliance could attract imprisonment of up to one year or fines of up to 10% of the property’s value; now, only monetary penalties apply. Importantly, the amendment is narrowly targeted — criminal penalties for developers and real estate agents under Sections 59-66 for promoter misconduct and project violations remain fully intact. The change is being welcomed as relief for middle-class homebuyers who had faced disproportionate legal risk over procedural lapses, while preserving RERA’s core builder-accountability framework.
THE BIGGER PICTURE
Taken together, today’s developments point to a market finding a new equilibrium: rate stability is anchoring buyer sentiment, infrastructure-led micro-markets like Noida are redrawing the price-growth map, developers are deploying capital confidently into land and new launches, and regulators are fine-tuning consumer protections without diluting oversight of builders. With festive-season demand approaching, all eyes will be on how these trends translate into sales momentum over the coming weeks.
—
This article has been compiled using AI-assisted research from publicly available real estate news, market reports and regulatory updates, under the byline of PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com.
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for RealNewsofIndia.com | August 15, 2026
NEW DELHI — India’s property sector had an eventful week, headlined by the Delhi Development Authority’s approval of the Master Plan for Delhi-2047, the Reserve Bank of India’s decision to hold the repo rate steady, and a buyer-friendly tweak to the RERA law that removes the threat of jail time for homebuyers. Here is a round-up of the developments shaping the country’s real estate market this week.
DDA APPROVES DELHI MASTER PLAN 2047, CLEARS WAY FOR 20 LAKH NEW HOMES
In the week’s biggest policy move, the Delhi Development Authority (DDA) has approved the Master Plan for Delhi-2047, envisaging roughly 20 lakh new flats across the capital to meet rising residential demand. The plan proposes land-pooling-led town planning across 105 villages, with about 69 of them brought under a new Green Development Area (GDA) policy that permits mixed residential and commercial use alongside conservation of parks, lakes, water bodies and biodiversity zones.
A major redevelopment component targets nearly 4 lakh ageing DDA flats for reconstruction, a move expected to benefit 30-40 lakh residents, subject to structural safety norms being met. The blueprint also allows regulated development along the Yamuna floodplain and opens up high-density construction within 250 metres of Urban Extension Road-2, the corridor running from Alipur through Dwarka to Mahipalpur.
The plan still requires clearance from the Union Ministry of Housing and Urban Affairs before it takes effect, but developers and analysts say it signals a substantial expansion of Delhi-NCR’s housing supply pipeline over the coming decades, along with fresh redevelopment opportunities for builders.
RBI HOLDS REPO RATE AT 5.25%, HOME LOAN EMIs STAY FLAT
The Reserve Bank of India’s Monetary Policy Committee, led by Governor Sanjay Malhotra, kept the repo rate unchanged at 5.25% in its August 2026 review, maintaining a neutral policy stance. For homebuyers, the pause means floating-rate and repo-linked home loan EMIs remain unchanged — for instance, a Rs 50 lakh loan at 9% interest over 20 years continues to carry an EMI of about Rs 44,986. While the decision offers no immediate relief through lower borrowing costs, it gives households predictability to plan big-ticket purchases without fear of a sudden rate hike, a factor real estate brokers say supports steady, if unspectacular, buyer sentiment heading into the festive season.
RERA AMENDMENT REMOVES JAIL PROVISION FOR HOMEBUYERS
Under the Jan Vishwas (Amendment of Provisions) Act, 2026, the government has amended Section 68 of the Real Estate (Regulation and Development) Act to remove the imprisonment clause that previously threatened homebuyers with up to a year in jail — or fines of up to 10% of the property’s value — for failing to comply with Real Estate Appellate Tribunal orders. Going forward, non-compliance will attract only monetary penalties. The change is being welcomed as major relief for middle-class buyers caught in builder disputes. Importantly, the amendment does not dilute accountability for the industry: imprisonment provisions for promoters and real estate agents under Sections 64 and 66 of RERA remain fully in force, as do penalties under Sections 59, 60, 61 and 63 for builder-side violations.
HOUSING SALES: MIXED SIGNALS FROM TOP CITIES IN Q2 2026
Two closely watched industry trackers have offered contrasting reads on the April-June 2026 quarter. PropEquity data shows housing sales across nine major cities rose 19% year-on-year to 1,12,458 units, with supply surging 43% to 1,17,609 units. Navi Mumbai (up 61%), Bengaluru (up 47%) and Mumbai (up 32%) led the gains, while Kolkata (down 23%) and Delhi-NCR (down 14%) lagged.
By contrast, ANAROCK’s report on the top seven cities shows sales falling 6% year-on-year to 90,715 units, with a sharper 11% sequential decline, which analysts attribute to cautious buyer sentiment amid West Asia-linked geopolitical tensions and supply-chain disruptions. New launches held up better, rising 7% annually to about 1,06,000 units, skewed heavily toward premium and luxury segments — homes priced above Rs 80 lakh accounted for nearly half of new supply, while affordable housing made up just 6%. City-wise, Kolkata (up 10%) and Hyderabad (up 2%) bucked the trend, while Pune (down 15%), Chennai (down 9%) and MMR (down 8%) saw the steepest drops.
Taken together, the divergent numbers point to a market that remains resilient in absolute terms but is increasingly bifurcated — supply is tilting toward premium and luxury housing even as affordability concerns persist for first-time buyers.
BROOKFIELD INDIA REIT, NCW FUND ACQUIRE MUMBAI BKC OFFICE SPACE FOR Rs 1,700 CRORE
In a sign of continued institutional appetite for prime commercial real estate, Brookfield India Real Estate Trust, along with the NCW fund, has agreed to acquire roughly 2.64 lakh square feet of office space in Mumbai’s Bandra-Kurla Complex (BKC) for approximately Rs 1,700 crore (about $170 million). BKC remains one of India’s tightest and most sought-after Grade-A office micro-markets, and the deal underscores the continuing flow of REIT and institutional capital into India’s commercial office segment even as global investors stay selective.
SECTOR OUTLOOK
Industry advisory Colliers has flagged infrastructure investment, sustained institutional capital and technology-led innovation as the three pillars likely to underpin Indian real estate through the rest of 2026, alongside continued momentum in Tier-1 and Tier-2 city expansion driven by metro connectivity and urban infrastructure upgrades.
Taken together, this week’s developments reflect a sector at an inflection point: expanding housing supply pipelines and stronger buyer protections on one hand, a cautious, premium-skewed sales environment on the other, and steady institutional confidence in commercial assets underpinning the broader market.
— Reported by AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for RealNewsofIndia.com
By AI Powered PMC Akbar Jiwani, Special Correspondent – Real Estate, Realnewsofindia.com
A new wave of investment is emerging as one of the most powerful, if underappreciated, growth engines behind India’s real estate expansion: the country’s booming data centre and AI infrastructure build-out. Where highways, metro corridors and IT parks anchored the last two decades of urban growth, industry analysts now say server farms and AI compute campuses are set to play a similar role over the next decade — and the numbers involved are staggering.
The scale of ambition was laid bare earlier this year when Adani Group chairman Gautam Adani announced a $100 billion commitment over the next decade to build AI-specialised data centres powered entirely by renewable energy, declaring that “India will not be a mere consumer in the AI age.” The plan, running through 2035, targets up to 5 gigawatts of dedicated data-centre capacity, with Adani projecting a further $150 billion in associated investment — taking the total AI infrastructure opportunity the group is chasing to roughly $250 billion. Large-scale campuses are already taking shape in Visakhapatnam and Noida, with expansion planned in Hyderabad and Pune, backed by tie-ups with global technology majors Google and Microsoft, an expanded partnership with Walmart-owned Flipkart, and a joint venture with US operator EdgeConneX that already runs 2 gigawatts of capacity. Underpinning all of it is Adani’s renewable energy portfolio, anchored by the 30-gigawatt Khavda solar project in Gujarat, with a further $55 billion earmarked for additional clean power and battery storage to keep the AI campuses running.
Adani is far from alone. India currently generates close to 20 per cent of the world’s digital data but hosts only about 4 per cent of global data centre capacity — a gap that global cloud providers, sovereign wealth funds and domestic conglomerates are racing to close as enterprise digitisation, cloud migration and AI workloads accelerate simultaneously.
For the real estate sector, the knock-on effects are now being quantified. A report by property platform Square Yards estimates that India’s data centre pipeline, currently pegged at roughly 9,030 megawatts of capacity, will generate close to 4.33 lakh jobs across the ecosystem and, in turn, drive demand for nearly 195 million square feet of residential real estate by 2030. That is a scale comparable to entire satellite townships springing up around what were, until recently, unremarkable industrial plots on city peripheries.
The demand is not expected to be evenly spread. Maharashtra is projected to see the single largest impact, with more than 54 million square feet of associated housing demand, reflecting Mumbai and Pune’s status as established data-centre hubs with power availability, submarine cable landing stations and connectivity infrastructure already in place. Karnataka, Andhra Pradesh, Uttar Pradesh, Telangana and Tamil Nadu are also flagged as major beneficiaries, tracking the same states where hyperscale campuses are being built out.
Rather than concentrating growth narrowly around the data centres themselves, the Square Yards report describes a “Golden Ring” effect — a belt spanning roughly 5 to 15 kilometres around major facilities where townships, mixed-use developments, retail and civic infrastructure are expected to flourish as ancillary employment (facility staff, engineers, logistics and support services) clusters nearby. Tier-2 and tier-3 locations such as Visakhapatnam, Noida and Gujarat’s GIFT City are being flagged as the next frontier of this trend, benefiting from improving connectivity, land availability and state-level incentives for digital infrastructure investment.
For developers and homebuyers alike, the implication is a structural one: digital infrastructure is emerging as a fresh anchor for real estate cycles, much as highways, airports and IT corridors were in previous booms. Analysts caution that translating power-and-compute investment into durable housing demand will still depend on states delivering the physical infrastructure — roads, water, schools and transit — needed to support new residential clusters at the pace capital is now flowing into AI infrastructure. But with tens of billions of dollars committed by a single conglomerate alone, and the broader industry racing to close India’s capacity gap with global peers, the data centre economy looks set to be one of the defining real estate growth stories of the second half of this decade.
This article has been written by AI powered PMC Akbar Jiwani Special Correspondent for Realnewsof India.com
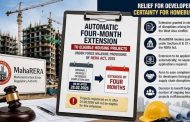
A regulatory order signed in New Delhi on the last day of July has quietly shifted the possession date on thousands of Indian homes. On 31 July 2026, the Union Ministry of Housing and Urban Affairs advised every state Real Estate Regulatory Authority to extend the registration and completion timelines of eligible registered projects by four months, invoking the force majeure provisions of the Real Estate (Regulation and Development) Act, 2016. Within a fortnight, MahaRERA, Haryana RERA and the Telangana authority had converted that advisory into blanket orders. For developers wrestling with disrupted supply chains, it is meaningful breathing room. For homebuyers already counting months, it is one more calendar page turned. Both readings are correct — and the gap between them is where the real story sits.
Background: What Section 6 Actually Permits
Section 6 of the RERA Act allows the registration granted to a project to be extended on the ground of force majeure. The statute does not leave the term to interpretation: it expressly contemplates war, flood, drought, fire, cyclone, earthquake and other calamities affecting the regular development of a project. Ordinarily the section is not self-executing — a promoter must apply to the concerned authority, project by project, and satisfy it that the disruption was genuine.
India has been here before. When the Ministry of Finance treated the COVID-19 pandemic as a force majeure event in 2020, a suo motu six-month extension followed for projects whose registration was expiring, and several state authorities — MahaRERA and Haryana RERA among them — granted extensions in the six-to-nine-month range without individual applications. That episode established both the mechanism and its limits, and its litigation legacy still shapes how tribunals read force majeure today.
Current Developments: The Chain of Orders
The current relief traces back to an Office Memorandum issued by the Department of Expenditure, Ministry of Finance, on 29 April 2026, which treated the prevailing situation in West Asia as war for the purpose of invoking force majeure. That classification was the legal hinge. Once war was formally recognised, Section 6 of RERA became available to the sector as a whole rather than to individual promoters pleading their own facts.
The Confederation of Real Estate Developers Associations of India had written to the Housing and Urban Affairs Secretary in April, seeking a blanket extension of three to six months and citing volatility in energy supplies that had disrupted production across key manufacturing clusters. The Ministry, in its 31 July advisory signed by Under Secretary (Housing) Sanjay Kumar, recorded that it had received representations from stakeholders regarding the impact of the prevailing situation in West Asia, which had adversely affected global supply chains, resulting in shortages of construction materials and impacting the timely completion of real estate projects.
The advisory sets a clear eligibility line. Registered projects whose completion date, revised completion date or extended completion date falls on or after 28 February 2026 receive four additional months. Critically, the Ministry recommended that states issue a single common order covering all eligible projects, precisely so that promoters would not have to file thousands of separate applications and authorities would not have to pass thousands of separate orders.
MahaRERA followed with a blanket order applying the extension automatically, with no separate application required from promoters — and with one important boundary: projects registered on or after 1 August 2026 are excluded, since a developer registering after the disruption was public knowledge cannot claim to have been surprised by it. Haryana RERA issued a parallel order for projects registered with it. The Telangana authority extended completion timelines for all eligible registered projects in the state on the same reasoning. In Uttar Pradesh, roughly 1,199 projects are reported to qualify, including about 301 in Noida and 148 in Ghaziabad — a useful indicator of the scale involved in a single state.
Detailed Analysis: A Section 6 Order, Not a Section 18 Amnesty
The most consequential feature of the 31 July circular is what it does not say. It addresses Section 6 alone — the extension of project registration on force majeure grounds. It does not advise authorities to grant an interest holiday for the four-month window, and it does not disturb a buyer’s entitlement to interest on refund when exiting a delayed project.
That distinction matters because Section 18 operates on a different logic. It entitles an allottee whose possession is delayed either to withdraw and receive a refund with interest, or to remain in the project and receive monthly interest for every month of delay. Nothing in Section 18 makes that liability conditional on, or subject to, a force majeure clause. The Supreme Court has said as much in unambiguous terms. In Imperia Structures Ltd v Anil Patni and in Newtech Promoters and Developers Pvt Ltd v State of Uttar Pradesh, the Court characterised the allottee’s right to interest at the prescribed rate as unqualified and indefeasible. MahaRERA’s own Model Agreement for Sale points the same way: Clause 6 does not exempt a promoter from interest liability merely because the delay arose from circumstances beyond the promoter’s control.
Promoters will nonetheless argue — not unreasonably at first glance — that if the state has declared a war, recognised force majeure and formally moved the completion date, interest cannot accrue during a period the regulator itself has excused. The counter-argument is that Section 6 governs the life of a registration while Section 18 governs a contractual and statutory obligation to the buyer, and that extending one does not extinguish the other. The honest position is that this remains legally untested. Until either the Housing Ministry issues a clarificatory circular or an appellate tribunal or High Court rules squarely on the point, it is a grey area — and grey areas in real estate are usually resolved by whoever litigates first.
Benefits: Why the Order Was Needed
The administrative case for a common order is strong. Filing individual Section 6 applications across tens of thousands of registered projects would have consumed regulatory bandwidth that authorities do not have, and would have delivered inconsistent outcomes to developers facing identical macro conditions. A single order applied uniformly is faster, cheaper and fairer than adjudicating the same fact pattern thousands of times over.
There is also a compliance benefit that is easy to overlook. A lapsed registration is not a paperwork problem — it stops marketing, complicates lender disbursements and can freeze sales in an otherwise healthy project. Keeping registrations valid keeps projects inside the regulated perimeter, where buyers retain their remedies. CREDAI president Shekhar Patel framed the extension as helping developers align completion timelines with the current market scenario while relieving them of the burden of filing separate applications, and argued that orderly execution safeguards all stakeholders, including homebuyers. NAREDCO likewise welcomed the regulatory clarity.
The macro context supports the argument that the sector is not in distress but in friction. MahaRERA approved 10,379 housing projects in FY26, with Pune and the Mumbai Metropolitan Region accounting for the largest share of new registrations — hardly the profile of a market retreating from supply. The constraint being addressed is input availability and logistics, not demand.
Challenges: The Buyer’s Objection
Homebuyer groups have not been persuaded, and their objection deserves to be stated at full strength. The Forum for Peoples Collective Efforts has argued that the advisory reflects an asymmetry in how the two sides of the transaction are treated: developers receive a one-size-fits-all regulatory accommodation issued from the top, while buyers servicing home loan EMIs and simultaneously paying rent receive no corresponding relief, no blanket protection and no automatic order in their favour.
The second and more practical concern is discrimination between projects. A blanket order cannot distinguish a developer genuinely stalled by a shortage of imported facade systems or specialised electromechanical equipment from one whose project was already running years late for reasons that predate February 2026 entirely. The 28 February cut-off is a blunt instrument, and a chronically delayed project inherits the same four months as a well-run one. Force majeure is meant to suspend obligations for the duration of the disrupting event, not to launder pre-existing default.
There is a third risk, subtler but real: precedent. Each blanket extension makes the next one easier to seek. COVID established the template; the West Asia conflict has now invoked it a second time. If sector-wide extensions become the routine answer to macro volatility, the deterrent effect of a hard RERA completion date begins to soften.
Expert Opinion
Advocate Shirish V Deshpande, chairman of the Mumbai Grahak Panchayat, has argued that the July circular concerns Section 6 alone and gives promoters no exemption from monthly interest for continuing delays in projects that were already delayed as of 28 February 2026, where buyers elect to remain. In his reading, force majeure may operate as a mitigating factor where a buyer seeks compensation over and above statutory interest, but it does not switch off the statutory interest itself. He has urged the Housing Ministry to issue a clarificatory circular stating its position, so that aggrieved parties can seek a final judicial determination on a settled record rather than litigating in the dark.
That call for clarity is, in editorial judgement, the single most useful thing that could happen next. Ambiguity here does not favour buyers or developers — it favours delay, and delay is the thing everyone claims to be trying to fix.
Future Outlook
Three developments are worth watching over the next two quarters. First, whether MoHUA issues the clarificatory circular on interest liability; its content will determine whether pending complaints settle or escalate. Second, whether appellate tribunals begin producing reasoned orders on the Section 6 versus Section 18 question — the first well-argued decision will set the tone. Third, whether the remaining states issue common orders, and whether they replicate MahaRERA’s 1 August registration cut-off, a sensible anti-gaming safeguard worth standardising nationally.
The broader signal is more encouraging than the headline suggests. A regulator that can absorb a genuine external shock through a transparent, published, uniformly applied order is functioning as intended. The failure mode would have been silence — registrations quietly lapsing, or thousands of inconsistent individual extensions granted behind closed doors.
Practical Takeaways
For homebuyers: check your allotment letter or agreement for sale against the MahaRERA portal to confirm the revised completion date now recorded for your project. The extension is automatic, so the portal date may have moved without any communication from your developer. If your project was already delayed before 28 February 2026, take written advice before assuming the extension has suspended your interest entitlement — on the current state of the law and the Supreme Court authority, it very likely has not.
For developers and promoters: no separate application is required, but the extension does not travel with the project automatically in every disclosure you make. Update your Form 3 and quarterly progress reporting, ensure sales teams and channel partners communicate the revised date accurately, and document the specific supply-chain disruption your project actually suffered. If interest liability is later contested, generic reliance on the common order will be far weaker than a project-level evidentiary record.
For cooperative housing societies in redevelopment: verify with your developer whether your project falls on the eligible side of the 28 February 2026 line, and insist that any revised timeline be reflected in a formal addendum to the development agreement rather than treated as an informal understanding. A regulatory extension does not by itself amend a contract between a society and its developer, and the two documents should not be allowed to diverge.
Conclusion
The four-month extension is a defensible administrative response to a genuine external disruption, delivered through the mechanism Parliament built into the statute for exactly this purpose. It is also, unmistakably, relief that moves in one direction. The Act’s architecture protects the buyer’s interest entitlement independently of the promoter’s registration timeline, and the Supreme Court has already said that entitlement is indefeasible. What is missing is an explicit official statement saying so. Issuing that clarification would cost the government nothing and would spare the sector a season of avoidable litigation. Until then, the sensible course for every party is the same one that has always served this industry best: read the order, read the statute, and do not assume the second follows the first.
Written by Ai Powered PMC Akbar Jiwani :Special correspondent for realestate www.akbarjiwanipmc.com
## Introduction
On 7 August 2026, the Maharashtra Real Estate Regulatory Authority did something it has done only sparingly in its nine-year history: it moved the finish line for thousands of housing projects at once. Invoking the force majeure provisions of the Real Estate (Regulation and Development) Act, 2016, MahaRERA extended the completion timelines of eligible registered real estate projects across the state by four months, citing the disruption to global supply chains caused by the ongoing conflict in West Asia.
The relief is automatic. Promoters do not have to file individual applications, and MahaRERA’s Registration and IT Cell has been tasked with updating project records and the public web portal to reflect the revised dates. For a state that accounts for the single largest concentration of RERA-registered housing supply in India, this is not a procedural footnote. It is a structural adjustment to how the market will read delivery promises for the rest of the year.
## Background: How a Distant Conflict Reached Maharashtra’s Construction Sites
The chain of causation is unusually well documented. The Department of Expenditure in the Union Ministry of Finance issued an office memorandum on 29 April 2026 treating the prevailing situation in West Asia as ‘war’ for the purposes of invoking the force majeure clause — a classification that carries weight across government contracting. That classification became the legal anchor for what followed.
On 31 July 2026, the Union Ministry of Housing and Urban Affairs issued an advisory asking all State Real Estate Regulatory Authorities to grant a four-month extension in the registration and completion timelines of eligible registered projects affected by the resulting disruption. Significantly, the Ministry recommended that state authorities issue a common order rather than process thousands of individual applications — a deliberate attempt to avoid the administrative bottleneck and litigation that piecemeal relief tends to produce. MahaRERA’s order a week later is the direct implementation of that advisory, and it sits alongside similar action by other state authorities, including Telangana’s TGRERA.
The mechanism itself is not new. Section 6 of the RERA Act permits extension of registration where completion is prevented by force majeure, and the sector has been here before. During the COVID-19 disruption, MahaRERA granted an automatic six-month extension with provision for a further discretionary three months, and treated the force majeure window as a moratorium for the purpose of computing delay. That precedent is instructive — and, as we shall see, contested.
## Current Developments: What the Order Actually Says
The eligibility test is a date test. Projects whose original completion date, revised completion date or previously extended completion date falls on or after 28 February 2026 receive the additional four months. Projects registered on or after 1 August 2026 are excluded — a sensible carve-out, since a developer registering after the disruption was already well known cannot claim to have been blindsided by it.
The scale is considerable. MahaRERA’s registry runs to tens of thousands of projects, and the Authority approved 10,379 real estate projects in FY2025-26 alone, a figure that covers new registrations, developer-requested timeline extensions and correction approvals. Nearly half of those approvals were concentrated in the Mumbai Metropolitan Region. Any blanket order in Maharashtra is therefore, disproportionately, an MMR order.
Industry bodies responded quickly and favourably. CREDAI president Shekhar Patel described the Centre’s advisory as a positive step in line with the sector’s ask, pointing to strained material and labour supply chains, and welcomed the common-order approach for ensuring uniform implementation across states. NAREDCO president Parveen Jain called it a balanced and much-needed step, urging states to implement it in letter and spirit to avoid unnecessary litigation. That last phrase is doing a lot of work, and deserves attention.
## Detailed Analysis: The Cost Curve Behind the Order
Force majeure relief is easier to justify when the underlying cost pressure is visible in the numbers, and here it partly is — though not uniformly. Material costs typically account for roughly 55 to 65 per cent of total construction cost in India, so shocks in that basket transmit quickly to project viability. Yet the picture through 2025 was mixed rather than uniformly inflationary: cement and steel prices were broadly soft, while aluminium and copper rose sharply on global demand. JLL has projected that construction costs across Indian asset classes will rise by three to five per cent in 2026.
The more persistent pressure is labour. Wage costs are expected to rise between five and twelve per cent following India’s new labour codes, which took effect in November 2025 and mandate improved social security, healthcare benefits and standardised wage structures. Read together, the picture is of a sector absorbing a slow, compounding squeeze on margins rather than a single dramatic price shock — with the West Asia disruption layered on top as an availability problem for specific imported inputs and logistics.
Financing conditions, by contrast, have been stable. The Reserve Bank’s Monetary Policy Committee, meeting on 5 August 2026 under Governor Sanjay Malhotra, held the repo rate unchanged at 5.25 per cent — the fourth consecutive pause, with elevated crude prices and global uncertainty cited among the reasons for caution. For developers, that means the cost of debt has not worsened; for buyers with repo-linked home loans, EMIs are broadly unchanged. Time, not money, is the variable that just moved.
## Benefits: Why the Order Makes Practical Sense
The strongest argument for the extension is that it substitutes an orderly, uniform administrative decision for a chaotic, case-by-case one. Without a common order, MahaRERA would have faced a wave of individual applications, each requiring scrutiny and each generating an appealable decision — consuming bandwidth that belongs to enforcement.
For developers, the relief removes the immediate threat of penalty and delay-interest exposure on projects whose slippage was genuinely attributable to supply disruption. That matters most for small and mid-sized promoters, who lack the balance-sheet depth to absorb both cost inflation and statutory interest simultaneously. Preventing distress at that end of the market is, indirectly, a homebuyer protection measure — a stalled project serves no one.
For the market as a whole, the order restores the credibility of published completion dates. A portal listing a date everyone privately knows is unachievable corrodes trust in the register itself. Resetting the dates transparently and on the record is preferable to letting a silent gap open between the register and reality.
## Challenges: The Homebuyer’s Legitimate Question
The obvious objection is that the buyer, who has done nothing wrong, absorbs the cost of a disruption she did not cause. Homebuyer groups have raised precisely this, demanding a waiver of interest on housing loans for the duration of projects granted force majeure extensions. The asymmetry is real: the developer’s clock stops, but the borrower’s EMI does not, and the rent-plus-EMI burden continues for four additional months.
There is also a real risk of over-claiming. A blanket date-based test cannot distinguish between a project genuinely dependent on disrupted imported inputs and one that was already years behind for reasons entirely unrelated to West Asia. The COVID-era experience is the cautionary precedent. Adjudicating authorities subsequently examined force majeure claims closely — in one widely discussed UP-RERA matter, the officer allowed roughly 476 days of justified delay after a detailed analysis of the actual restrictions, and then held the promoter accountable for the delay beyond it. Force majeure has been read as a shield for the period of genuine disruption, not as a general amnesty.
The legal architecture also remains intact beneath the order. Section 18 of the RERA Act continues to give an allottee the right to withdraw and claim refund with interest and compensation where possession is not handed over, or to claim monthly interest for delay if she chooses to stay in the project. The Supreme Court has also held that homebuyers may seek relief under both RERA and the Consumer Protection Act. An administrative extension recalibrates the reference date; it does not extinguish statutory rights, and NAREDCO’s warning about implementation ‘in letter and spirit’ is, read carefully, an acknowledgement that sloppy application will end up in tribunals.
## Expert Opinion
The considered view among practitioners is that the order should be read narrowly and applied honestly. The Centre’s own framing is instructive: the relief is directed at projects ‘affected by disruptions arising from’ the West Asia situation, and the date-based test is an administrative proxy for that condition, not a replacement for it. A promoter who invokes the extension while unable to demonstrate any actual supply-side impact is inviting scrutiny later, when an aggrieved allottee tests the claim before the Authority or an appellate forum.
The second observation is that documentation is now the developer’s cheapest insurance. Purchase orders, supplier correspondence on lead times, import invoices, evidence of material substitution and site-level progress records are what will distinguish a defensible force majeure position from an opportunistic one if the matter is litigated. Cooperative housing societies engaged in redevelopment — a large and growing share of MMR supply — should be asking their developers for exactly this evidence now, while it is easy to produce, rather than in three years, when it is not.
## Future Outlook
The demand side of the market gives little sign of flinching. Mumbai recorded 13,617 property registrations in July 2026, an 8.3 per cent increase year-on-year and the highest July figure in fourteen years, according to data from the Maharashtra Department of Registrations and Stamps analysed by Knight Frank India. Registrations rose from 13,413 in June, while stamp duty collections climbed from ₹1,086 crore in June to ₹1,223 crore in July — an 8.9 per cent rise over July 2025 and a 13 per cent sequential increase. Revenue growing faster than volume points to a continuing shift towards higher-value homes.
That combination — resilient demand, stable policy rates and a four-month cushion on delivery — suggests the extension will be absorbed by the market rather than disrupt it. The more interesting question is what happens at the end of the window. If supply chains normalise, the reset dates should hold and the episode will read as competent, pre-emptive administration. If disruption persists into 2027, the sector will return with a second request, and the Authority will face a harder decision: repeated extensions begin to erode the deterrent value of the deadline itself, which is the single most important thing RERA gave homebuyers.
## Practical Takeaways
For homebuyers, the first step is factual, not emotional: check the project’s MahaRERA page over the coming weeks and record the revised completion date the Authority publishes. Preserve the allotment letter and agreement for sale, which contain the contractual possession date, and note that the statutory right to interest for delay survives beyond the extended date. Where the delay predates February 2026, the extension does not retrospectively cure it.
For developers and promoters, the practical instruction is to treat the extension as a reprieve requiring evidence rather than a free pass. Update quarterly project progress reports accurately, communicate revised timelines to allottees in writing rather than letting them discover the change on the portal, and build a contemporaneous file on the specific supply disruptions the project experienced.
For managing committees of cooperative housing societies in redevelopment, this is the moment to convene the developer and reconcile three documents: the development agreement’s timeline, the MahaRERA-revised date, and the transit rent obligation. Extensions to the completion date do not automatically extend a developer’s liability for transit accommodation unless the agreement says so — and that gap is where society redevelopment disputes most often begin.
## Conclusion
MahaRERA’s four-month extension is, on balance, sound regulatory practice: a transparent, uniform, publicly recorded adjustment in response to a documented external shock, delivered through a single order rather than thousands of contested applications. It keeps the public register honest and prevents an avoidable wave of technical defaults.
Its legitimacy, however, will be determined entirely by how it is used. Applied to projects genuinely constrained by disrupted supply chains, it is proportionate relief. Applied as cover for delays that have nothing to do with West Asia, it becomes exactly the kind of dilution of accountability that RERA was enacted to end. Maharashtra’s homebuyers have every reason to accept the extension — and every reason to hold the industry to the promise implicit in it.






Recent Comments