




By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Tier-II Cities Fuel India’s Land-Buying Boom: Transactions Surge 132x as Developers Chase ₹16.67 Lakh Crore Revenue Opportunity
Mumbai, September 11, 2026: India’s land-buying market has entered a new phase of growth, with fresh data from global property consultancy Cushman & Wakefield showing that annual land transactions in the country’s smaller Tier-II cities have exploded 132-fold over the past five years — outpacing the traditional metro markets and signalling a structural shift in where developers see the next wave of opportunity.
According to the report, which tracked 892 land deals across 33 cities between 2021 and the first quarter of 2026, India recorded a cumulative 18,158 acres of land transactions over the period. Annual volumes rose from just 813 acres in 2021 to 6,181 acres in 2025 — a compound annual growth rate of roughly 66 per cent — with another 1,194 acres already changing hands in Q1 2026 alone. Cushman & Wakefield estimates the land parcels transacted so far carry a potential revenue opportunity of ₹16.67 lakh crore, translating into roughly 1.4 billion square feet of future built-up development.
Smaller cities lead the charge
The standout finding is the rise of Tier-II markets such as Coimbatore, Indore, Visakhapatnam, Ludhiana, Panipat and Nagpur. In 2021, these cities accounted for barely 16 acres of annual land transactions — about 2 per cent of the national total. By 2025, that figure had jumped to 2,120 acres, or 34 per cent of all transactions nationally. The average deal size in Tier-II cities also grew sharply, from 8 acres in 2021 to 53 acres in 2025, even as the average Tier-I deal size shrank from 21 acres to 10 acres over the same period, reflecting land scarcity and rising prices in the larger metros. Tier-I cities still command the lion’s share of cumulative acreage at 71 per cent, but the trend line is unmistakably tilting toward smaller urban centres.
Where the land is going
Residential development remains the single largest end-use, accounting for 45 per cent of land acquired, with potential built-up area estimated between 559 and 768 million square feet. Industrial and logistics land use has also surged, making up 27 per cent of deals in 2024-25, while office-linked land purchases have grown nearly fivefold — from 76 acres in 2021-22 to 384 acres in 2024-25 — as developers position for a broader commercial recovery. Data centre-linked land acquisition is emerging as a fast-growing new category, with potential built-up area pegged at 113-124 million square feet, while retail remains the smallest segment.
On deal structure, outright purchases continued to dominate at over 60 per cent (10,910 acres), but joint ventures and development agreements are gaining ground fast — rising from just 11 such deals in 2021 to 42 in 2025 — as land prices climb and developers look to share capital risk rather than pay upfront.
Infrastructure push and Make in India driving demand
The report attributes much of the momentum to a combination of expanding infrastructure capital expenditure, employment generation, and manufacturing growth under government initiatives such as Make in India and production-linked incentive (PLI) schemes, alongside rising e-commerce and modern retail demand and improving expressway connectivity into smaller cities.
“Economic growth, infrastructure capex and employment generation are driving the expansion in land transactions,” said Somy Thomas, Executive Managing Director, Capital Markets, Cushman & Wakefield. He cautioned, however, that the rapid price appreciation of recent years may not be sustainable everywhere: “Land prices have reached a critical level in several locations, making it harder to sustain the same rate of appreciation.” On the shift toward partnerships, Thomas added: “Once land prices become high, it is more attractive to partner rather than deploy expensive capital upfront.”
Outlook
Notably, 2025’s transaction volume was 1.6 times the previous peak recorded in 2024, underscoring how quickly the market has accelerated. With institutional debt largely unavailable for raw land purchases, domestic developers continue to dominate deal-making, financing acquisitions through internal accruals, equity and joint-development structures. Going forward, Cushman & Wakefield expects the pace of price appreciation to vary widely by micro-market, hinging on local economic activity and the pace of infrastructure rollout — with India’s expanding network of expressways and industrial corridors likely to keep pulling capital toward Tier-II and even Tier-III destinations in the years ahead.
Reported by AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
M3M Outbids DLF to Win Rs 1,850-Crore Noida Land Parcel, Signalling Fresh Investor Confidence in NCR Realty
Noida, September 10, 2026: In one of the most closely watched land auctions in the National Capital Region this year, Gurugram-based developer M3M India has emerged as the highest bidder for a prime 12.5-acre mixed-use plot in Sector 108, Noida, offering Rs 1,850 crore — a premium of roughly 121 per cent over the Noida Authority’s reserve price of Rs 835 crore. The result, declared this week, saw M3M see off stiff competition from real estate major DLF Ltd, while a third shortlisted contender, Godrej Properties, chose to sit out the final round of bidding.
The Sector 108 parcel works out to a price of nearly Rs 147-148 crore per acre, among the steepest per-acre valuations recorded for a single land parcel in Noida in recent years. Once stamp duty and other statutory charges — estimated at close to Rs 150 crore — are factored in, M3M’s total outlay for the site is expected to approach Rs 2,000 crore, according to a Noida Authority official cited in local reports. The land is earmarked for an integrated residential-cum-commercial development that will feed into M3M’s expanding footprint along the Delhi-NCR corridor, complementing its existing portfolio of projects along the Dwarka Expressway.
The Sector 108 win was not M3M’s only move this week. The developer also secured a separate six-acre parcel in Sector 98 for Rs 414 crore, taking its combined fresh land investment in Noida to more than Rs 2,400 crore in a matter of days. Industry watchers describe the twin acquisitions as among the largest single-developer land commitments in the NCR in recent memory, underscoring how aggressively top-tier builders are now competing for well-located parcels as end-user and investor demand in the region continues to firm up.
The auction result also fits into a broader pattern of renewed institutional and corporate appetite for Noida land. It follows closely on the heels of Godrej Properties’ acquisition of a 4.95-acre residential plot in Sector 151 for Rs 331.75 crore, and comes at a time when Noida and Greater Noida have consistently featured among the top-performing micro-markets in the National Capital Region for both capital appreciation and rental yields, aided by improving connectivity via the Noida-Greater Noida Expressway, the upcoming Noida International Airport at Jewar, and sustained infrastructure push from the state government.
For the Noida Authority, the bumper realisation — well over double the base price — is also a fiscal win, adding significantly to the civic body’s revenue kitty that is ploughed back into infrastructure augmentation, road widening and civic amenities across the city. Sharp premiums of this kind in Authority-led auctions have increasingly become the norm rather than the exception this year, reflecting both scarcity of well-located, fully serviced land parcels and developers’ eagerness to build up inventory ahead of an anticipated upcycle in NCR housing demand.
For homebuyers and investors tracking the Noida market, the message from this week’s auction is unambiguous: marquee developers are willing to pay a significant premium to secure a foothold in Sector 108 and its neighbouring micro-markets, a strong signal that fresh, large-format residential and mixed-use supply — and the infrastructure investment that typically follows it — is on its way to one of the National Capital Region’s fastest-growing corridors.
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
India’s push to clear the backlog of stalled residential projects is entering its most consequential phase yet, as the government moves to formally operationalise SWAMIH Fund-2, a ₹15,000 crore vehicle designed to complete roughly one lakh additional housing units for homebuyers who have been waiting years for possession.
WHAT IS HAPPENING
Finance Minister Nirmala Sitharaman has told Parliament that “formal steps to operationalise the fund are under way,” with the government finalising governance arrangements, investment parameters and disbursement mechanisms before capital begins flowing to stalled sites. The fund, announced in Union Budget 2026-27, will be managed by SBICAP Ventures Ltd and structured as an Alternative Investment Fund that provides priority debt financing to RERA-registered, brownfield residential projects — largely in the affordable and mid-income segments — where construction has stalled due to financial stress, legal disputes or developer default. The finance ministry has also held coordination meetings with banks, LIC and other institutional lenders to widen the fund’s capital base and scope.
WHY THE GOVERNMENT IS DOUBLING DOWN
The case for a sequel fund rests on the track record of the original SWAMIH Fund, launched in November 2019 and also managed by SBI’s investment arm. According to government data, the first fund has:
– Raised a total corpus of ₹15,530 crore and unlocked more than ₹37,400 crore in capital across 127-plus stalled projects
– Delivered around 61,000 to 63,200 completed homes, out of a total portfolio pipeline of roughly 1,01,443 units across 145-plus projects in 30-plus cities, covering more than 90 million square feet
– Generated over ₹6,900 crore in tax revenue for the Centre and states through GST, stamp duty and other statutory payments, while returning nearly half of drawn capital to investors, including ₹3,500 crore to the government
– Created more than 36,000 jobs, with 3,520 permanent positions and 15% female workforce participation, alongside secondary demand of roughly 20 lakh tonnes of cement and 5.5 lakh tonnes of steel
Affordable and EWS (economically weaker section) housing accounted for a significant share of this delivery — government figures put affordable housing at 44% of the fund’s portfolio, with more than 7,000 EWS units handed over to buyers.
WHY IT MATTERS FOR THE SECTOR
Stalled projects have long been one of the most persistent drags on confidence in Indian real estate, tying up homebuyers’ savings for years while eroding trust in under-construction purchases. SWAMIH-2 extends a model that market participants and analysts credit with directly improving sentiment: by injecting last-mile financing rather than equity, the fund completes units without requiring distressed developers to dilute ownership, while giving homebuyers a credible, government-backed pathway to possession.
Real estate industry voices, including developers such as Hiranandani, have pointed to SWAMIH-2 alongside other recent measures — such as changes to TDS on rentals — as part of a broader set of structural tailwinds for the sector this year. Combined with the Unified RERA portal rolled out to standardise regulatory disclosures nationally, and state-level digitisation drives such as Maharashtra’s move to embed GIS-based land records in property sale deeds from October, the SWAMIH-2 rollout adds another layer to the government’s multi-pronged effort to make Indian real estate more transparent, more bankable for institutional capital, and less risky for the ordinary homebuyer.
With formal operationalisation now in progress, the coming months will be watched closely for the first tranche of SWAMIH-2 disbursements — a milestone that could determine how quickly the next wave of stalled projects, and the families waiting on them, finally get to move in.
By AI-Powered PMC Akbar Jiwani, Special Correspondent – Real Estate, for RealNewsOfIndia.com
n a fresh signal that India’s real estate growth story is expanding well beyond its traditional metro strongholds, Mumbai-headquartered developer Prime Group has announced plans to invest approximately ₹1,500 crore in Bihar’s real estate sector over the next four quarters, marking the company’s first major entry into the state and adding to a growing list of developers betting on India’s under-penetrated Tier-2 markets.
The group, which currently operates across Mumbai, Bengaluru, Kolkata and Ranchi, plans a development pipeline of roughly 5 million square feet of residential and mixed-use projects in Bihar. Explaining the rationale behind the move, the company’s Chairman said: “Bihar is entering an important phase of real estate growth, and we see significant opportunity in the market.”
Prime Group, which operates on a zero-debt balance sheet, said the financial flexibility this affords will support its scale-up plans in the new market. The company has also engaged investors from the Middle East along with overseas architects and specialist consultants as part of its Bihar expansion, with further project-level details expected to be announced in the coming months.
Why Bihar, and Why Now
The move is emblematic of a broader shift in India’s property market. For over a decade, institutional and developer capital has concentrated overwhelmingly in the National Capital Region, Mumbai Metropolitan Region, Bengaluru, Pune and Hyderabad. That pattern is now visibly changing, as improving connectivity infrastructure, rising urban incomes, a maturing regulatory framework under the Real Estate (Regulation and Development) Act (RERA), and state governments actively courting investment have made states like Bihar, Uttar Pradesh and Madhya Pradesh increasingly attractive to organised developers.
This trend has been visible through the past week alone: separate reports have pointed to Uttar Pradesh’s real estate investment climbing sharply this year, Mumbai’s property registrations touching a 14-year August high, and continued Centre-level support for stalled housing projects through the SWAMIH Fund. Taken together, these developments point to a real estate sector that is broadening its growth base geographically even as established hubs continue to perform strongly.
For Bihar specifically, a mid-sized, RERA-registered developer of Prime Group’s scale committing four-figure-crore capital is a notable vote of confidence. It suggests organised, branded real estate — long dominated by local and regional builders in the state — is now attracting pan-India players who typically enter a market only once they see durable demand, improving ease of doing business, and adequate legal and regulatory safeguards for buyers.
What It Means for Homebuyers and Investors
For prospective homebuyers in Bihar, the entry of an established, financially stable developer with a zero-debt balance sheet is likely to be a reassuring development, given how project delays and buyer disputes have historically been a concern in less-organised markets. For investors, it reinforces a wider thesis gaining currency among analysts: that India’s next leg of real estate growth will be driven as much by Tier-2 and Tier-3 cities as by the traditional metro corridors, as affordability pressures in established markets push both developers and buyers to look further afield.
As more details of Prime Group’s Bihar projects emerge over the coming quarters — including specific project locations, launch timelines and pricing — the move will be closely watched as a bellwether for whether large-scale organised real estate investment can successfully take root in one of India’s fastest-urbanising but historically under-invested states.
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Mumbai, September 6, 2026 — In a move set to reshape how property is bought, sold and verified across India, the Maharashtra government has cleared a plan to embed Geographic Information System (GIS) maps directly into property sale deeds, replacing the decades-old practice of describing plot boundaries through vague landmarks and directions. The reform, submitted by the state’s Department of Land Records, will roll out from October 2026 in ten pilot districts before a phased statewide expansion, and comes even as the Centre works in parallel with states on a nationwide GIS-linked registration framework expected within two years.
Under the new system, every property earmarked for registration in the pilot districts will first undergo “Mojini” — a formal digital land measurement — using the K-Prat land-measurement platform, which will be integrated directly with the registration department’s systems. High-resolution satellite imagery accurate to roughly 30 centimetres will anchor the initial mapping, to be followed by ground-level resurveys that combine ownership records, building footprints and parcel-level data into a single verifiable digital layer.
For a real estate market that has long grappled with boundary disputes, overlapping land claims and title fraud arising from ambiguous deed language, the shift is significant. Officials associated with the initiative say GIS-linked sale deeds will “enhance transparency, improve citizen confidence, and make property transactions more secure and efficient” — language that echoes the Centre’s broader push to tie every transaction to an accurately mapped land parcel, given how large a share of the economy land and property dealings represent.
The reform builds on Maharashtra’s recent run of digitisation measures, including Aadhaar-linked registration and streamlined stamp-duty processing, and follows a string of government interventions elsewhere strengthening buyer protection this year — from the Unified RERA portal launched to bring greater transparency to project disclosures, to RERA’s tightened three-account escrow rule governing how developers manage project funds, to a Supreme Court directive requiring developers to deliver projects exactly as depicted in sales brochures. Together, these measures point to a regulatory environment increasingly focused on documentation integrity and homebuyer confidence, at a time when developers such as Max Estates, Prime Group and Brigade Group continue to announce large land acquisitions and project launches across the country.
Why it matters: Title disputes and unclear boundaries remain among the most common reasons property transactions in India stall, end up in litigation, or collapse altogether. A GIS-anchored deed gives buyers, lenders and developers a single, satellite-verified reference point for a parcel’s exact location and extent — reducing due-diligence time, lowering fraud risk, and potentially easing the flow of institutional capital into markets where title uncertainty has historically kept valuations and financing conservative. If the Maharashtra pilot succeeds and the Centre’s nationwide framework follows on schedule, digital mapping could become as central to property transactions in India as RERA registration has become over the past decade — a structural, transparency-driven tailwind for the sector rather than a one-time policy headline.
By AI-Powered PMC Akbar Jiwani, Special Correspondent – Real Estate, Realnewsofindia.com
ASK Property Fund, the real estate investment arm of the Blackstone-backed ASK Asset & Wealth Management Group, has committed ₹300 crore to two residential housing projects in Ghaziabad, in a fresh signal that investor confidence in the National Capital Region’s mid-market housing corridor continues to strengthen even as the wider Indian residential sector heads into a premiumisation-led growth cycle.
The investment is split between two established Ghaziabad micro-markets. Around 4.7 acres of the funding will go towards BRV Group’s residential project in Vasundhara, while a further parcel of 1.5 acres backs KW Group’s development in Indirapuram — both long-established, end-user-driven residential belts within the Ghaziabad-NCR corridor.
Explaining the rationale behind the deal, Bhavin Jain, Co-Head and Chief Investment Officer at ASK Property Fund, said Ghaziabad is “emerging as one of the NCR’s most compelling residential markets, supported by deep end-user demand, attractive ticket sizes and transformative connectivity through the Delhi-Meerut Expressway, Namo Bharat Rapid Rail, Metro links, the existing airport and planned connectivity to the Jewar Airport.”
Industry watchers note that Vasundhara and Indirapuram already benefit from mature social infrastructure — schools, hospitals and retail — and sit within commuting distance of employment hubs spread across Ghaziabad, Noida and Delhi. The rapid build-out of regional rail and expressway links is widely seen as the key catalyst re-rating these older NCR neighbourhoods in the eyes of institutional capital, which has traditionally favoured Gurugram and Noida.
The transaction adds to what has been a steady run of capital deployment for ASK Property Fund, which has raised roughly ₹10,000 crore since its inception in 2009 and today manages assets exceeding ₹85,000 crore, as of July 31, 2026.
Part of a broader growth story
The Ghaziabad commitment lands against the backdrop of an upbeat sector-wide outlook. Ratings agency ICRA has projected that premiumisation will drive 8-11% growth in the value of home sales across India in FY27, even as the area sold grows at a slower pace of 2-5% — underscoring a market where buyers are trading up rather than simply buying more space. Private equity and institutional investors have been following that demand upstream into Tier-2 NCR micro-markets such as Ghaziabad, betting that improved connectivity and affordability relative to Gurugram and Noida will sustain end-user absorption through FY27 and beyond.
Taken together with recent momentum in Uttar Pradesh’s real estate investment pipeline and record stamp-duty collections in markets such as Mumbai, the Ghaziabad deal reinforces a broader narrative: India’s residential real estate sector is entering FY27 on a foundation of stronger institutional capital flows, improving infrastructure connectivity, and a shift toward premium, well-located housing stock.

By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Government’s ₹15,000-Crore SWAMIH Fund II Set to Rescue 1 Lakh Stalled Homes, Reinforcing India’s Real Estate Recovery
NEW DELHI, September 4, 2026: In one of the most consequential government interventions for India’s real estate sector in recent years, the Centre’s SWAMIH Investment Fund II — backed by a ₹15,000 crore corpus — is progressing toward full rollout with a mandate to complete construction on nearly 1 lakh (100,000) housing units stuck in stalled, RERA-registered projects across the country. The initiative, first unveiled in the Union Budget, is being positioned by policymakers and industry leaders alike as a decisive step in restoring stalled-housing confidence and sustaining the momentum behind India’s broader real estate growth story.
What the Fund Does
SWAMIH Fund II follows the “last-mile financing” model pioneered by its predecessor: rather than funding new construction, it provides priority debt financing to complete projects where homebuyers have already paid substantial sums but face indefinite delays due to funding shortfalls, legal entanglements, or execution hurdles. Eligible projects must be registered under the Real Estate (Regulation and Development) Act (RERA) and fall largely within the affordable and mid-income housing segments — the categories where stalled inventory has hit homebuyers hardest.
Finance Minister Nirmala Sitharaman informed Parliament that the fund “is being set up to support completion of stalled housing projects” and confirmed it is “in the process of being formally launched” following extensive consultations with public sector banks, private lenders and institutional investors. The fund follows a blended-finance structure, drawing capital from the central government alongside contributions from banks and financial institutions including the State Bank of India, Life Insurance Corporation of India, Canara Bank, HDFC Bank and other major lenders, who were brought into the design process specifically to shape the fund’s structure and eligibility criteria based on lessons learnt from the original scheme. SBICAP Ventures Ltd, which has managed the programme since its inception, continues as fund manager.
A Track Record to Build On
The credibility of SWAMIH Fund II rests heavily on the demonstrated success of SWAMIH Fund I, launched in November 2019 as India’s largest real estate stress fund. As of the most recent disclosures, Fund I has secured a corpus of ₹15,530 crore, committed investments across 148 projects, and built a portfolio spanning 1,01,443 homes nationwide — of which more than 63,200 units have already been completed and handed over to long-waiting homebuyers, with thousands more slated for delivery this year.
Industry voices have welcomed the sequel fund enthusiastically. Niranjan Hiranandani, Chairman of NAREDCO, noted that “SWAMIH Fund One was very successful, and a large number of projects were started or had been cleared by that scheme,” adding that Fund II’s ₹15,000 crore central government contribution “will be further strengthened by contributions from banks and financial institutions” — a structure he believes will materially deepen its impact on the ground.
Why It Matters for India’s Real Estate Growth
Stalled housing projects have long represented one of the most persistent drags on confidence in Indian real estate, tying up homebuyer savings for years and denting sentiment in the very affordable and mid-income segments the government has prioritised under its housing-for-all agenda. By targeting last-mile completion rather than fresh construction, SWAMIH Fund II is designed to convert dead capital into delivered homes relatively quickly, unlocking both immediate relief for distressed homebuyers and a fresh wave of completed inventory that feeds directly into the sector’s overall growth numbers.
Coming on the heels of strong state-level momentum — including record project registrations and investment surges reported recently out of Uttar Pradesh and Maharashtra — the fund underscores a broader pattern in 2026: a real estate sector being propelled not just by fresh private investment, but by sustained, targeted government intervention aimed at fixing structural bottlenecks. As the formal rollout of Fund II proceeds, the coming months will be watched closely for the first tranche of project approvals and the pace at which stalled units convert into keys handed over to India’s homebuyers.
This article is written by AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Four months after it took effect, the decriminalisation of Section 68 of the Real Estate (Regulation and Development) Act, 2016 (RERA) is emerging as one of the more consequential — and contested — reforms to India’s real estate regulatory architecture in recent years, with legal commentators now sharpening their critique of what the change actually delivers for homebuyers.
What changed. Section 68 previously allowed criminal prosecution — up to one year’s imprisonment, on top of daily fines that could cumulatively reach 10 per cent of a property’s cost — against any party, allottee or promoter, who failed to comply with an order of a RERA Appellate Tribunal. Under the Jan Vishwas (Amendment of Provisions) Act, 2026, that imprisonment clause has been removed entirely. Non-compliance now attracts only a monetary penalty, capped at up to 10 per cent of the cost of the plot, apartment or building, to be levied through administrative adjudication rather than a criminal court. The Ministry of Housing and Urban Affairs formally notified the change with effect from May 7, 2026 (notification S.No. 70), following the Bill’s passage by the Lok Sabha on April 1, 2026.
Part of a much larger clean-up. The RERA change is one small piece of a sweeping legislative exercise: the Jan Vishwas (Amendment of Provisions) Act, 2026 decriminalises minor, technical non-compliances across 79 central laws and 784 provisions — nearly four times the scope of the original 2023 version of the Act, which had covered 42 laws and 183 provisions. The government’s stated philosophy, as reflected in the amendment’s framing, is that criminal law should not be the default response to regulatory lapses, and that enforcement should move from magistrates’ courts to faster, more accessible administrative officers wherever the underlying conduct does not involve fraud or wilful violation.
A federal wrinkle. Because real estate sits on the Concurrent List of the Constitution, this central amendment automatically overrides state-level RERA frameworks. States will need to formally notify their own adjudicating officers to administer the new civil-penalty mechanism, replacing the earlier practice of routing non-compliance cases to magistrates — a transition industry watchers say could take months to complete uniformly across states.
The pushback. Not everyone in the legal fraternity is convinced the reform addresses what actually ails RERA enforcement. A widely circulated critique published in Bar and Bench argues that the criminal penalty under Section 68 was, in practice, barely ever invoked in RERA’s nine years of existence — making its removal largely symbolic. The real grievance for homebuyers, the column contends, lies elsewhere: recovery certificates issued under Section 40 to enforce refund orders against defaulting developers routinely sit with district collectors for months or years without yielding results, while criminal provisions against errant promoters under Sections 63 and 64 are rarely invoked to begin with. Critics also point to the Supreme Court’s 2025 ruling in Mansi Brar Fernandes, which flagged persistent staffing and expertise gaps within RERA authorities and tribunals — structural problems that a legislative tweak to Section 68 does nothing to resolve. The broader worry, as framed in the column, is that the amendment nudges RERA’s character further toward “a statute about doing business” and away from its founding mandate as a homebuyer-protection law.
Why it matters for the sector. For developers and allottees alike, the shift to civil penalties is likely to be read as a net positive on paper — it reduces the coercive weight hanging over allottees who fall foul of tribunal orders, and aligns with the government’s broader ease-of-doing-business push ahead of India’s real estate sector eyeing sustained double-digit growth through the rest of the decade. But the debate now unfolding among legal practitioners is a reminder that headline decriminalisation numbers do not, by themselves, translate into faster refunds, better-staffed tribunals, or stronger accountability for non-performing promoters — the issues that continue to dominate homebuyer grievances across RERA authorities nationwide.
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Uttar Pradesh Real Estate Investment Surges 53% to ₹68,328 Crore in 2025, UP RERA Data Shows
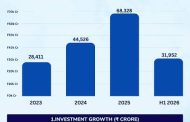
Mumbai, September 2, 2026: Uttar Pradesh’s real estate sector has recorded its strongest year on regulatory record, with capital investment in RERA-registered projects climbing 53.5% to ₹68,328 crore in 2025, up sharply from ₹44,526 crore in 2024, according to data released by the Uttar Pradesh Real Estate Regulatory Authority (UP RERA). The figures mark the third consecutive year of double-digit growth, with investment having stood at just ₹28,411 crore in 2023 — meaning the state’s registered real estate capital base has more than doubled in two years.
The number of RERA-registered projects in the state rose 19% to a record 308 in 2025, up from 259 the previous year and 197 in 2023. Approved housing and commercial supply climbed in tandem, with 84,976 units cleared for construction in 2025 — a 22.5% jump over 2024’s 69,365 units, and taking cumulative supply added since 2023 past the 255,000-unit mark. Of the 2025 total, 62,672 units were residential (flats, plots and villas) and 22,304 were commercial (shops and studio spaces).
What distinguishes this cycle from earlier boom years is its geographic spread. UP RERA data shows registered projects now span 27 districts, up from 23 in 2024, with 186 of the 308 projects — well over half — located outside the National Capital Region. Western UP led with 175 projects worth ₹55,620.43 crore, followed by Central UP at 104 projects and ₹11,270.42 crore, and Eastern UP at 29 projects and ₹1,436.86 crore. Noida remained the single largest contributor with 69 projects, 37,199 units and ₹37,161 crore in investment, but non-NCR hubs are now registering meaningful volumes of their own: Lucknow logged 67 projects and ₹9,398 crore, Ghaziabad 29 projects worth ₹12,750 crore, while Mathura, Bareilly and Agra each crossed into double-digit project counts.
Momentum has carried into the current year. UP RERA figures for the first half of 2026 show roughly ₹32,000 crore in fresh capital investment across 158 projects, adding close to 46,000 housing units to the pipeline — a pace that, if sustained, would put 2026 on track to rival or exceed 2025’s full-year total.
UP RERA Chairman Sanjay Bhoosreddy attributed the sustained growth to the regulator’s twin focus on market discipline and buyer protection, saying project registrations and housing supply “reflect growing confidence among developers and investors,” while stressing the authority’s continued emphasis on “balanced regional development, timely completion of projects and safeguarding the interests of homebuyers.” Regulatory enforcement has run alongside the growth: UP RERA has facilitated the recovery and transfer of ₹1,623 crore to 6,411 homebuyers through its recovery proceedings mechanism since inception, underscoring the compliance architecture developers now operate under in the state.
Why it matters: Uttar Pradesh’s trajectory offers a counterpoint to the narrative that Indian real estate growth is concentrated in a handful of metro markets. With state capital investment nearly matching the scale seen in several established metro RERA jurisdictions, and with more than half of new projects now originating outside the NCR belt, the data points to a genuine broadening of formal, RERA-compliant real estate activity into Tier-2 centres such as Lucknow, Varanasi, Agra and Mathura — cities benefiting from expressway connectivity, the Uttar Pradesh Real Estate Investment Policy push, and religious-tourism-linked demand in pilgrimage circuits. For developers and investors tracking India’s next wave of urban growth beyond Mumbai, Delhi-NCR and Bengaluru, UP RERA’s 2025 numbers are a clear signal that the state’s real estate formalisation story is accelerating, not plateauing.
—
This article is written by AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com

By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Mumbai’s residential real estate market closed August 2026 on a strong note, with property registrations within the Brihanmumbai Municipal Corporation (BMC) limits projected at 12,503 units — an 11% year-on-year increase and the highest figure recorded for the month of August in over 14 years, according to fresh data from the Maharashtra Department of Registrations and Stamps, analysed by Knight Frank India.
The surge in registrations translated into robust revenue for the state exchequer, with stamp duty collections for the month pegged at ₹1,123 crore, up 12% compared to the same period last year.
A strong month, even with a sequential dip
August’s numbers follow an even stronger July 2026, when Mumbai recorded 13,824 registrations — an 8.3% year-on-year rise that itself marked a 14-year high for that month, with stamp duty collections of ₹1,255 crore. Measured against July, August registrations were down roughly 10%, and stamp duty revenue eased about 11% sequentially — a pattern Knight Frank attributes to a natural moderation after an unusually high comparison base, rather than any underlying weakness in demand.
“Mumbai’s residential market continues to see healthy demand, with August 2026 projected to record the highest property registrations for the month in over 14 years,” said Shishir Baijal, Chairman and Managing Director, Knight Frank India. He added that while collections have moderated sequentially from July’s peak, the strong year-on-year performance underscores the housing market’s resilience, with well-located developments backed by quality infrastructure remaining the most attractive to buyers as they grow more selective.
Rohan Khatau of CCI Projects echoed the sentiment, noting that the sustained growth in registrations reflects a more discerning buyer base and a redefinition of what constitutes a “well-located” home in Mumbai, as infrastructure upgrades reshape buyer preferences across the city.
What is driving the momentum
Industry trackers point to a combination of factors sustaining Mumbai’s registration volumes through 2026: continued end-user demand backed by the city’s economic depth and employment base, a steady pipeline of project completions and possession-linked registrations, and growing buyer confidence in real estate as a long-term investment amid infrastructure expansion across the Mumbai Metropolitan Region. Improved connectivity projects and redevelopment activity in the city’s older housing stock have also widened the base of “well-located” inventory available to buyers, supporting registration volumes even as affordability pressures persist in the city’s core micro-markets.
Why it matters
Mumbai’s monthly registration and stamp duty data is widely tracked as a real-time barometer of housing demand in India’s most valuable property market, and consistent double-digit year-on-year growth — sustained now across both July and August 2026 — suggests the city’s residential upcycle, underway since the post-pandemic recovery, retains momentum heading into the festive season, traditionally the strongest stretch for Indian home sales. Sustained stamp duty collections are also a meaningful revenue source for the Maharashtra government, reinforcing the fiscal case for continued state support to housing and infrastructure initiatives across the Mumbai Metropolitan Region.
With the festive season — historically the period of peak home-buying activity in India — set to begin in the coming weeks, developers and brokers will be watching closely to see whether Mumbai can convert this sustained registration momentum into a strong September-to-December stretch.






Recent Comments