



By AI-Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
ndia’s housing market is heading into the Navratri-Dussehra-Diwali stretch on a note of cautious optimism, as a fresh round of industry data and a large buyer-sentiment survey both point to steady — if slower-growing — demand through the rest of 2026.
BUYERS ARE WILLING, BUT PRICE-CONSCIOUS
According to the Colliers Homebuying Sentiment Survey 2026, “Decoding India’s Evolving Buyer Preferences,” which polled roughly 1,800 respondents across more than 30 established and emerging residential markets, around half of prospective buyers say they intend to purchase a home within the next two years. A majority, 54 per cent, believe global macroeconomic volatility will have a relatively limited impact on Indian real estate, underlining the sector’s growing insulation from external shocks.
The survey found that affordability remains the single biggest concern for buyers, cited by roughly a third of respondents, followed closely by job security and income visibility. Even so, demand is concentrated in a fairly accessible band: 46 per cent of respondents said they were looking at homes priced between ₹50 lakh and ₹1.5 crore, and 62 per cent preferred 2-3 BHK configurations. Larger units are finding favour in Delhi-NCR, Bengaluru and Hyderabad, while Mumbai buyers continue to lean toward more compact homes given price pressures in the city.
Notably, more than 60 per cent of buyers said they now prefer ready-to-move-in or near-completion properties over under-construction projects — a preference that skews stronger among buyers over 30, while younger, under-30 buyers appear more comfortable absorbing construction-linked risk in exchange for early-stage pricing.
“Housing sales going forward will depend on price-value alignment, financing flexibility and product-market fit,” said Ravi Shankar Singh, Managing Director, Residential Transaction Services at Colliers India. Vimal Nadar, National Director and Head of Research at Colliers India, added that the festive season is expected to sustain buyer interest, but developers “will need to align product offerings” more closely with what affordability-conscious buyers can absorb.
FESTIVE PIPELINE: MODERATING GROWTH, NOT A SLOWDOWN
Separately, projections from Knight Frank India and Anarock suggest the coming festive quarter (July-September and the Dussehra-Diwali window) will see sales modestly ahead of the preceding quarter, even as the pace of year-on-year growth cools compared with the exuberance of the past two years. Knight Frank’s Vivek Rathi noted that festival-period sales in 2026 are expected to exceed 2025 levels, with new launches across the top eight cities already up 4 per cent year-on-year in the first half of the year. Anarock’s Santhosh Kumar projects third-quarter sales across the top seven cities running 3-4 per cent above the second quarter, with new launches potentially up to 10 per cent higher year-on-year.
Developers are lining up accordingly. Gurugram-based Signature Global plans two launches worth ₹10,000-12,000 crore timed for Dussehra and Diwali, as it targets ₹10,000 crore in FY27 pre-sales. Embassy Developments is readying close to ₹10,000 crore worth of new projects, concentrated largely in Bengaluru, even as it expects overall industry sales to stay broadly flat year-on-year. Smaller and mid-sized players, including Smartworld Developers and Bengaluru-focused Krishvi Group, say premium and luxury segments — homes priced upward of ₹1.5 crore, and in some cases above ₹10 crore — are likely to see the strongest festive-season traction.
An Anarock consumer poll of over 8,200 homebuyers reinforces the affordability theme: 65 per cent said they were moderately concerned about rising prices, and 40 per cent see the increases as a long-term trend rather than a temporary spike. Yet 44 per cent said they would proceed with a purchase regardless. Demand for homes priced above ₹1.5 crore has more than doubled over five years, rising to 27 per cent of buyers in the first half of 2026 from just 13 per cent in the first half of 2021 — a sign of the market’s continuing shift toward premiumisation even as affordability concerns persist at the entry level.
POLICY BACKDROP STAYS SUPPORTIVE
The demand outlook is being underpinned by a stable policy environment: the Reserve Bank of India has held its repo rate steady at 5.25 per cent through recent reviews, keeping home-loan costs predictable heading into the festive season, while earlier GST rationalisation on key construction inputs such as cement and marble/granite has trimmed input costs for developers. Taken together, industry watchers say the ingredients are in place for a healthy, if more measured, festive season — one defined less by frenzied volume growth and more by how well developers price and position their projects for a buyer base that is willing to purchase, but increasingly doing the arithmetic first.
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for RealNewsofIndia.com
India has moved into the “Transparent” tier of global property markets for the first time, climbing five places to rank 26th out of 88 countries in JLL’s Global Real Estate Transparency Index (GRETI) 2026 — up from 31st in the previous edition. The jump makes India the best-improving real estate market in the Asia-Pacific region this cycle and places it among the world’s top five most-improved markets, according to the report released this week.
The GRETI, published every two years by property consultancy JLL, scores 146 city markets across 88 countries on a scale of 1 to 5 using 260 individual factors covering regulation, transaction processes, listed-market performance and sustainability disclosure. Lower scores indicate greater transparency. India’s climb was driven overwhelmingly by reform in its regulatory and legal framework, where the country jumped from 37th to 19th place globally — its strongest single-category gain — and from 9th to 6th within Asia-Pacific.
“India did not just improve this year; it set the pace for Asia Pacific,” said Radha Dhir, CEO of JLL India. “Moving from 31st to 26th globally and ranking among the top five most-improved markets worldwide reflects a market that is compounding gains, not chasing a single good year.”
Officials at JLL attributed the gains to a decade of overlapping reforms: the maturing of the Real Estate (Regulation and Development) Act, or RERA; liberalised foreign direct investment norms; the Digital Personal Data Protection Act; measures in the Union Budget 2026-27; and a push toward digitised land records through the National Urban Digital Mission, the NAKSHA platform and the Digital India Land Records Modernisation Programme. The report also credited SEBI’s Business Responsibility and Sustainability Reporting framework and the National Green Building Mission, launched in 2025, with lifting India’s sustainability score from 29th to 27th globally.
Capital markets data released alongside the index underline the shift. Private equity inflows into Indian real estate touched $10.5 billion in 2025, a 17 per cent rise year-on-year, with a further $4.3 billion in the first half of 2026 alone — up 25 per cent on the same period last year. Direct investment over the past twelve months hit $8.1 billion, JLL said, a 20-year high for the sector.
“The direct investment we saw this year, a 20-year high, is not the ceiling; it is the foundation we are building on,” said Lata Pillai, JLL’s Senior Managing Director and Head of Capital Markets, India. Pillai pointed to India’s real estate investment trust (REIT) market as a particular bright spot: listed office REIT stock has grown 58 per cent, from 104 million square feet in 2024 to 164 million square feet in 2026, with close to half of the country’s Grade A office stock now considered REIT-worthy.
Sustainability metrics also improved sharply on the ground. The share of green-certified Grade A office space in India rose from roughly 39 per cent in 2020 to 66 per cent in the first half of 2026, with certified buildings now commanding rental premiums of 10 to 15 per cent over uncertified stock — a signal that occupiers and investors are increasingly pricing in environmental compliance.
The report flagged the country’s fast-growing data centre sector as a related growth pole: current capacity of roughly 1.6 gigawatts is projected to nearly quadruple to 6 gigawatts by 2029, requiring an estimated $110 billion in fresh capital.
Even with the leap forward, JLL cautioned that India remains short of the “Highly Transparent” tier occupied by markets such as the United Kingdom, France, Australia, the United States and the Netherlands, which topped this year’s index. The report identified gaps still to close: voluntary rather than mandatory Scope 3 emissions disclosure, the absence of formal building-performance and public energy-usage disclosure regulation, no biodiversity-risk reporting standards, and the need to extend the Green Building Mission beyond new construction to existing stock. JLL’s suggested path forward includes deeper fund-structure disclosure, stronger credit-market intelligence, verified real-time building-performance data and wider use of AI-driven due diligence tools.
For India’s real estate sector — long criticised by global investors for opacity around land titles, project delays and regulatory inconsistency — the GRETI 2026 result offers concrete evidence that a decade of legislative and digital reform is beginning to show up in the numbers that matter most to institutional capital.
India’s real estate sector has recorded its strongest transparency gain in years, climbing five places to rank 26th in the world on the JLL Global Real Estate Transparency Index (GRETI) 2026, entering the index’s “Transparent” tier for the first time and topping the improvement charts across the entire Asia-Pacific region, according to findings released this week.
The country was named among the top five most-improved real estate markets globally, jumping from 31st position in the previous edition of the index. A key driver behind the leap was a sharp improvement in India’s regulatory environment, with its regulatory sub-ranking surging from 37th to 19th — a shift analysts attribute to the maturing of the Real Estate Regulatory Authority (RERA) framework, liberalised foreign direct investment (FDI) norms, and the rollout of digital land-record systems including the National Urban Digital Mission.
“India did not just improve this year in JLL’s Global Real Estate Transparency Index 2026; it set the pace for Asia Pacific. Moving from 31st to 26th globally and ranking among the top five most-improved markets worldwide reflects a market that is compounding gains, not chasing a single good year,” said Radha Dhir, CEO of JLL India.
CAPITAL IS FOLLOWING THE CONFIDENCE
The transparency gains have coincided with a marked rise in investor appetite. Private equity investment into Indian real estate touched $10.5 billion in 2025, a 17 per cent year-on-year increase, while direct investment into the sector hit a 20-year high of $8.1 billion over the trailing twelve months.
“The direct investment we saw this year, a 20-year high, is not the ceiling; it is the foundation we are building on. Private equity flows are already up 17 per cent year-on-year, reaching $10.5 billion in 2025,” said Lata Pillai, Senior Managing Director and Head of Capital Markets, India, at JLL.
The office segment has been a particular beneficiary of this renewed confidence. REIT-worthy office stock — Grade A office space suitable for real estate investment trusts — has expanded 58 per cent to 164 million square feet in 2026, up from 104 million square feet in 2024, with nearly half of all Grade A office space in the country now meeting REIT-grade standards.
Looking further ahead, the report projects India’s data centre capacity will nearly quadruple from 1.6 gigawatts to 6 gigawatts by 2029, a build-out expected to require roughly $110 billion in capital investment and to push the market further toward the index’s “Highly Transparent” category in future editions.
A REGULATORY ENVIRONMENT STILL IN MOTION
The transparency gains arrive alongside continued fine-tuning of India’s real estate regulatory architecture. Earlier this year, the Jan Vishwas (Amendment of Provisions) Act, 2026 — a central government initiative aimed at easing compliance burdens across multiple economic laws — amended Section 68 of the RERA Act to remove the threat of imprisonment for homebuyers who fail to comply with orders of the Real Estate Appellate Tribunal, leaving only monetary penalties in place. Imprisonment provisions for developers and real estate agents under other sections of the Act remain unchanged, meaning builder accountability under RERA continues as before while buyers gain relief from what was widely seen as a disproportionate penal risk.
Taken together, industry watchers say the twin developments — a stronger global transparency ranking and a regulatory system recalibrating in favour of consumers without diluting developer accountability — point to a real estate market maturing on both the investment and consumer-protection fronts simultaneously.
OUTLOOK
With India now inside the “Transparent” tier for the first time and posting the fastest improvement of any Asia-Pacific market, real estate watchers will be tracking whether the momentum in regulatory reform, digital land governance and capital inflows can be sustained through the rest of 2026 — a run that JLL’s own leadership describes not as a peak, but as a foundation for further gains.
India’s real estate sector has recorded its strongest transparency gain in years, climbing five places to rank 26th in the world on the JLL Global Real Estate Transparency Index (GRETI) 2026, entering the index’s “Transparent” tier for the first time and topping the improvement charts across the entire Asia-Pacific region, according to findings released this week.
The country was named among the top five most-improved real estate markets globally, jumping from 31st position in the previous edition of the index. A key driver behind the leap was a sharp improvement in India’s regulatory environment, with its regulatory sub-ranking surging from 37th to 19th — a shift analysts attribute to the maturing of the Real Estate Regulatory Authority (RERA) framework, liberalised foreign direct investment (FDI) norms, and the rollout of digital land-record systems including the National Urban Digital Mission.
“India did not just improve this year in JLL’s Global Real Estate Transparency Index 2026; it set the pace for Asia Pacific. Moving from 31st to 26th globally and ranking among the top five most-improved markets worldwide reflects a market that is compounding gains, not chasing a single good year,” said Radha Dhir, CEO of JLL India.
CAPITAL IS FOLLOWING THE CONFIDENCE
The transparency gains have coincided with a marked rise in investor appetite. Private equity investment into Indian real estate touched $10.5 billion in 2025, a 17 per cent year-on-year increase, while direct investment into the sector hit a 20-year high of $8.1 billion over the trailing twelve months.
“The direct investment we saw this year, a 20-year high, is not the ceiling; it is the foundation we are building on. Private equity flows are already up 17 per cent year-on-year, reaching $10.5 billion in 2025,” said Lata Pillai, Senior Managing Director and Head of Capital Markets, India, at JLL.
The office segment has been a particular beneficiary of this renewed confidence. REIT-worthy office stock — Grade A office space suitable for real estate investment trusts — has expanded 58 per cent to 164 million square feet in 2026, up from 104 million square feet in 2024, with nearly half of all Grade A office space in the country now meeting REIT-grade standards.
Looking further ahead, the report projects India’s data centre capacity will nearly quadruple from 1.6 gigawatts to 6 gigawatts by 2029, a build-out expected to require roughly $110 billion in capital investment and to push the market further toward the index’s “Highly Transparent” category in future editions.
A REGULATORY ENVIRONMENT STILL IN MOTION
The transparency gains arrive alongside continued fine-tuning of India’s real estate regulatory architecture. Earlier this year, the Jan Vishwas (Amendment of Provisions) Act, 2026 — a central government initiative aimed at easing compliance burdens across multiple economic laws — amended Section 68 of the RERA Act to remove the threat of imprisonment for homebuyers who fail to comply with orders of the Real Estate Appellate Tribunal, leaving only monetary penalties in place. Imprisonment provisions for developers and real estate agents under other sections of the Act remain unchanged, meaning builder accountability under RERA continues as before while buyers gain relief from what was widely seen as a disproportionate penal risk.
Taken together, industry watchers say the twin developments — a stronger global transparency ranking and a regulatory system recalibrating in favour of consumers without diluting developer accountability — point to a real estate market maturing on both the investment and consumer-protection fronts simultaneously.
OUTLOOK
With India now inside the “Transparent” tier for the first time and posting the fastest improvement of any Asia-Pacific market, real estate watchers will be tracking whether the momentum in regulatory reform, digital land governance and capital inflows can be sustained through the rest of 2026 — a run that JLL’s own leadership describes not as a peak, but as a foundation for further gains.

INDIA CLIMBS TO 26TH SPOT IN GLOBAL REAL ESTATE TRANSPARENCY RANKINGS, EMERGES ASIA-PACIFIC’S TOP IMPROVER
By AI Powered PMC Akbar Jiwani, Special Correspondent – Real Estate, Realnewsofindia.com
India has entered the ranks of the world’s top 30 most transparent real estate markets for the first time, climbing five places to 26th position globally in the 2026 Global Real Estate Transparency Index (GRETI) published by property consultancy JLL, moving the country into the index’s “Transparent” tier and marking one of the sharpest year-on-year gains recorded anywhere in the world.
The GRETI report, which scores 88 countries and 146 city markets across 260 individual factors, ranked India among the top five most-improved real estate markets globally and named it the single best-performing market in the Asia-Pacific region this cycle. JLL data also shows India posting the fourth-best transparency improvement globally over a ten-year horizon and the third-best over twenty years, underlining a sustained rather than one-off climb up the rankings. The United Kingdom topped the 2026 index, followed by France, Australia, the United States and the Netherlands.
“India did not just improve this year; it set the pace for Asia Pacific,” said Radha Dhir, Chief Executive Officer, India, JLL. “Moving from 31st to 26th globally and ranking among the top five most-improved markets worldwide reflects a market that is compounding gains, not chasing a single good year.”
The report credits a cluster of government-led reforms for the jump. The maturing implementation of the Real Estate (Regulation and Development) Act (RERA) across states was cited as a central driver, alongside continued liberalisation of foreign direct investment norms in the sector. Digitisation of land records also featured prominently, with JLL pointing to the National Urban Digital Mission (NUDM), the NAKSHA scheme and the Digital India Land Records Modernisation Programme (DILRMP) as measures that have improved title clarity and reduced transaction friction. Investment provisions in the Union Budget 2026-27, along with expanding renewable and nuclear energy capacity targets tied to infrastructure growth, were also flagged as supporting factors.
The steepest gain came in the regulatory and legal transparency sub-index, where India jumped from 37th to 19th place globally, and from 9th to 6th within Asia-Pacific, the single largest sub-category improvement in this year’s report. India’s transaction-process ranking held steady at 10th globally and 3rd in Asia-Pacific, while its listed-market score edged up marginally from 36th to 35th. On sustainability, India improved to 27th globally from 29th, helped by the SEBI-mandated Business Responsibility and Sustainability Report (BRSR) framework, the National Green Building Mission launched in 2025, and the phased rollout of the Digital Personal Data Protection Act.
The transparency gains coincide with a marked rise in investor appetite. According to Lata Pillai, Senior Managing Director and Head of Capital Markets, India, at JLL, direct real estate investment into India touched a 20-year high of 8.1 billion dollars over the past twelve months. “The direct investment we saw this year, a 20-year high, is not the ceiling; it is the foundation we are building on. Private equity flows are already up 17 per cent year-on-year, reaching 10.5 billion dollars in 2025,” Pillai said, adding that private equity inflows rose a further 25 per cent year-on-year to 4.3 billion dollars in the first half of 2026 alone.
Pillai also pointed to rapid expansion in India’s listed real estate space: office REIT stock has grown 58 per cent, from 104 million square feet in 2024 to 164 million square feet in 2026, with nearly half of the country’s Grade A office stock now considered “REIT-worthy.” Separately, JLL estimates India’s data centre pipeline will require 110 billion dollars in capital by 2029, with capacity projected to quadruple from 1.6 gigawatts to 6 gigawatts over the same period. Green-certified Grade A office stock has risen from roughly 39 per cent in 2020 to 66 per cent in the first half of 2026, with certified buildings now commanding rental premiums of 10 to 15 per cent over non-certified space.
Looking ahead, JLL laid out four priorities it believes could push India from “most improved” to what Pillai described as “genuinely institutional grade”: deepening disclosure standards across fund structures and asset classes beyond office real estate, strengthening credit-market intelligence, establishing real-time building-performance metrics, and deploying artificial intelligence to streamline due diligence processes.
For India’s real estate sector, long characterised by fragmented records and regulatory unevenness across states, the GRETI 2026 ranking offers an independent, internationally benchmarked signal that reform efforts of the past decade are translating into measurable, investor-facing outcomes – a trend that, if sustained, could further accelerate institutional capital flows into Indian property markets in the years ahead.
(Data and quotes sourced from JLL’s Global Real Estate Transparency Index 2026 report, as reported by Business Standard and The Week, September 18, 2026.)
— Ends —

By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
New Delhi, September 18, 2026: India’s real estate sector has entered the second half of 2026 on its strongest institutional footing in years, with fresh data confirming that the country’s property investment market not only hit a record high in the first half of the year but is also being led overwhelmingly by domestic capital — a shift analysts say marks a structural maturing of the Indian real estate story.
According to the latest half-yearly capital markets report, India’s real estate sector attracted equity capital inflows of USD 8.5 billion in H1 2026, up 32 per cent year-on-year from USD 6.4 billion in H1 2025 — the highest half-yearly figure on record for the sector. The momentum held through the second quarter as well, with Q2 2026 alone accounting for USD 3.4 billion, broadly stable compared with the same quarter last year.
What stands out most for market watchers is the composition of this capital. Domestic investors accounted for nearly 92 per cent of Q2 2026 inflows, with global investors making up the remainder — a marked departure from earlier cycles when foreign institutional capital dominated Indian real estate deal-making. Within that domestic pool, developers contributed roughly 34 per cent of capital infusion, while domestic institutional investors accounted for close to 32 per cent. Institutional investor capital inflows specifically rose 51 per cent quarter-on-quarter in Q2 2026, pointing to sharpening conviction among large domestic funds.
Land and development-site acquisitions, together with built-up office assets, made up roughly 94 per cent of total equity investment inflows in the quarter. More than 88 per cent of the capital directed toward site and land acquisitions flowed into residential and office developments, with the balance spread across data centres, mixed-use projects, and industrial and logistics assets — sectors that continue to draw steady, if smaller, allocations as India’s digital infrastructure and supply-chain buildout gathers pace.
Geographically, the growth story remains concentrated in India’s established investment hubs. Bengaluru, Delhi-NCR and Mumbai together accounted for nearly 60 per cent of total inflows during the quarter, underscoring how office demand, tech-sector expansion and residential absorption in these three markets continue to anchor investor decision-making. Separately, new investment and development platforms worth approximately USD 1.6 billion were set up during the period across the residential and office sectors, signalling that large investors are structuring long-term vehicles rather than making one-off bets.
Commenting on the trend, Anshuman Magazine, Chairman and CEO – India, South-East Asia, Middle East and Africa, CBRE, said: “This momentum reflects the underlying resilience and depth of India’s real estate capital markets. Domestic investors have continued to demonstrate strong conviction in the sector’s long-term fundamentals, even as the broader environment remains dynamic. We expect this momentum to carry into the second half of the year, with select foreign capital expected to re-engage as global conditions stabilise.”
Gaurav Kumar, Managing Director & Co-Head, Capital Markets, India, CBRE, added: “India’s real estate investment landscape continues to demonstrate sustained growth with strong institutional investments in core assets and hectic activity in land transactions. Global investors and domestic players have been unanimous in their aggressive intent in expanding their real estate portfolios across all asset classes. We expect the market to sustain this momentum going forward on account of a sophisticated capital pool that is now deeply committed to the Indian Real Estate Market.”
The record inflows have also translated into outsized market share for individual advisory firms. In a separate update dated September 17, 2026, CBRE disclosed that it captured a 55 per cent share of all tracked investment sales activity across property types in India during H1 2026 — more than half the entire market, per data from MSCI Real Assets. The firm’s dominance was even starker in specific segments: a 77 per cent share in development-site transactions and a 100 per cent share in apartment and residential asset sales. Globally, CBRE ranked as the No. 1 firm for commercial real estate investment sales with a 23 per cent share, and topped the Asia-Pacific league table with a 33 per cent share — an 1,100-basis-point lead over its nearest competitor, alongside top rankings in Australia, Hong Kong SAR, Japan, New Zealand and Thailand.
“Commanding more than half of India’s investment sales market is a strong signal of the confidence investors continue to place in CBRE,” Magazine said of the H1 league-table performance. “Our leadership reflects where and how we see the strongest capital flows in India today, and we expect that momentum to continue through the second half of 2026.”
For India’s broader property sector, the takeaway is twofold: capital availability is no longer the constraint it once was, and the investor base underpinning that capital has become distinctly more domestic and more institutional in character. With residential and office assets continuing to draw the lion’s share of money, and logistics, data centres and mixed-use developments building a steady base beneath them, industry watchers expect 2026 to close as one of the strongest years yet for Indian real estate capital markets — provided global conditions stay stable enough to draw the foreign capital that executives say is waiting on the sidelines.
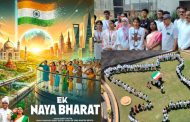
Citizens come together with the Tricolour to mark the ‘Seva Sankalp Abhiyan’
Mumbai, September 18, 2026:
A striking display of national unity and public participation was witnessed in Andheri, Mumbai, where citizens and participants came together to create a giant human formation depicting the vision of “Viksit Bharat” (Developed India).
The programme was organised as part of the ‘Seva Sankalp Abhiyan’, a government initiative aimed at connecting citizens with public welfare schemes and services and encouraging public participation.
According to the official communication issued by the Office of the Tahsildar and Executive Magistrate, Andheri, a taluka-level human-rangoli programme was organised on September 17, 2026, at 12 noon at the Rajiv Gandhi Institute of Technology, Juhu-Versova Link Road, H.D.F.C. Bank Marg, Four Bungalows, Andheri West, Mumbai.
Tricolour at the Centre, ‘Viksit Bharat’ at the Heart
The most eye-catching feature of the event was the large human formation created on the ground. Participants stood together in carefully arranged lines, forming the message of “Viksit Bharat”, while the Indian Tricolour was prominently displayed at the centre.
The aerial photograph of the formation captured the scale of participation and presented a powerful visual of people coming together around the idea of nation-building.
Participants from different groups joined the activity, turning the programme into a collective expression of unity, civic participation and national development.
A Message Beyond a Photograph
The human formation was more than a visual presentation. It conveyed the idea that the journey towards a developed India involves participation from citizens across different sections of society.
The official letter also called for the organisation of human rangoli based on public welfare schemes, national symbols and the concept of Viksit Bharat as part of the campaign.
‘Reels of India’ Adds a Digital Dimension
The programme was also covered through Reels of India, with a special song/reel created around the theme of Viksit Bharat.
Through photographs, video and music, the initiative brings the message of the programme to audiences beyond the physical venue. Such digital storytelling can provide an additional platform for documenting public participation and community activities.
Andheri Witnesses a Visual Symbol of Collective Participation
The sight of hundreds of participants standing together in formation, with the Tricolour at the centre, created a memorable scene at the Andheri venue.
From the official campaign communication to the giant human formation and its digital presentation through Reels of India, the event brought together government initiative, citizen participation and creative communication on one platform.
The aerial image of the formation now stands as a distinctive visual record of the ‘Viksit Bharat’ message presented in Andheri.
— Real News of India
Special News Coverage
Chief Reporter: S.M. Fanus
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Jan Vishwas Act Strips Jail Threat from RERA — But Legal Experts Ask If It Fixes the Real Problem
Homebuyer-penalty reform notified this year removes imprisonment under RERA Section 68, even as critics say India’s real estate regulator was never the one throwing buyers in jail — developers who defy orders are.
By AI-Powered PMC Akbar Jiwani, Special Correspondent — Real Estate, Realnewsofindia.com | New Delhi, September 17, 2026
India’s real estate regulatory framework has quietly gained one of its most talked-about tweaks since RERA itself came into force nearly nine years ago. Under the Jan Vishwas (Amendment of Provisions) Act, 2026 — an omnibus reform passed by the Lok Sabha on April 1 and the Rajya Sabha a day later — Section 68 of the Real Estate (Regulation and Development) Act, 2016 has been amended to remove the threat of imprisonment for allottees, that is, homebuyers, who fail to comply with orders passed by the Real Estate Appellate Tribunal. The Ministry of Housing and Urban Affairs formally notified the change into force on May 7, 2026. Only a monetary penalty now survives, capped at 10 per cent of the cost of the plot, apartment or building in question.
The change is part of a much larger legislative sweep. The Jan Vishwas Act amends 784 provisions across 79 central laws overseen by 23 ministries, decriminalising 717 of them and reforming another 67 — replacing jail terms for minor, procedural or first-time offences with revised fines. Commerce and Industry Minister Piyush Goyal, steering the umbrella bill through Parliament, called it “a significant step towards simplifying laws, reducing compliance burden and fear of penalties,” adding that “a nation will only progress through trust but not through fear.”
For India’s property sector — still working through a post-pandemic wave of delayed projects, stressed developers and cautious homebuyers — a reform that eases the coercive edge of RERA compliance sounds, on its face, like good news. It fits neatly into the government’s wider ease-of-doing-business and ease-of-living narrative, and arrives even as the Ministry has separately extended project registration and completion timelines for developers under RERA this year, a move CREDAI and NAREDCO welcomed.
But the Section 68 change specifically has drawn a sharper, more skeptical read from legal commentators. Writing in Bar and Bench, advocates Kshitij Saruparia and Apeksha Kachhawaha argue the amendment solves a problem that barely existed. Their review of the Ministry’s own Status Tracker — covering roughly 1.47 lakh disposed RERA complaints since 2017 — found no recorded instance of an allottee ever being prosecuted, let alone jailed, under Section 68. “Policymakers removed a liability homebuyers never actually faced,” their column notes, while the provision’s other, arguably more consequential half — used against promoters and developers under Sections 59 to 64 and 66 for defying regulatory and appellate orders — remains untouched.
That distinction matters to anyone tracking the ground reality of RERA enforcement. The recurring complaint from homebuyers who do win their cases is not fear of jail, but the opposite: winning an order and then waiting years to actually recover money or possession, because execution of recovery certificates routes through district magistrates who are frequently slow, under-resourced, or simply unresponsive. Critics argue that a dedicated execution mechanism within RERA itself, or direct attachment powers for state authorities, would have addressed a genuine gap. Reader reactions on the same legal commentary echoed the point: several called for RERA to be strengthened further, describing the appellate process as still tilted toward developers on matters of delayed possession.
What it means going forward: buyers should not read this as a weakening of their protections — the substantive remedies under RERA, from compensation to project-completion orders, are unchanged, and no allottee was losing sleep over jail time to begin with. Developers, for their part, see no additional relief here either, since the criminal exposure that has historically worried promoters sits in sections the amendment did not touch. The more consequential story for the sector, in other words, may not be this month’s headline reform, but whether the government’s next move addresses the execution bottleneck that homebuyers and legal experts alike say is RERA’s real unfinished business.
Sources: SCC Online Blog (May 9, 2026); Corpzo; News on Air (Rajya Sabha proceedings); Bar and Bench column, “Jan Vishwas and the wrong end of RERA.”
By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
India’s residential real estate market is entering the festive season on firm footing, with fresh industry data showing that home prices across the country’s top eight cities have stayed above the ₹10,000 per square foot mark for a second consecutive quarter, even as sales volumes cooled slightly from a year earlier. Combined with a steady interest-rate environment and GST relief on key construction inputs, the sector is being described by analysts as “maturing, not weakening.”
WHAT THE DATA SHOWS
According to the Real Insight Residential report for Q2 2026 released by PropTiger.com (part of listed real estate technology firm Aurum PropTech Limited), the top eight cities together recorded 91,729 housing units sold against 89,161 new launches during the quarter.
Sales fell 4.4% quarter-on-quarter and were down 6.1% compared with 97,674 units sold in the same quarter last year.
New launches, however, rose 6.0% year-on-year from 84,138 units.
The sales-weighted average price across the eight cities rose 1.0% quarter-on-quarter to ₹10,153 per square foot, holding above the ₹10,000 threshold for the second straight quarter.
City-wise, the Mumbai Metropolitan Region remained the largest market by both volume and value, with 24,112 units sold and prices up 20.4% year-on-year to ₹15,422 per square foot. Bengaluru posted the steepest annual price rise among the eight cities at 26.0%, even as sales there slipped 9.2%. Pune crossed the ₹8,000 per square foot mark for the first time, up 13.7% year-on-year, while Ahmedabad remained the most affordable large market at ₹5,295 per square foot but logged the sharpest sequential price gain, up 7.0% quarter-on-quarter. Kolkata led sequential sales growth nationally with a 22.0% quarter-on-quarter rise, which the report attributes to a post-election demand recovery, and Chennai recorded a 36.0% year-on-year jump in sales even as new supply fell 43.3%. Hyderabad and Delhi-NCR were comparatively stable, with Hyderabad launches up 21.6% year-on-year.
WHY PRICES ARE RISING DESPITE SOFTER SALES
PropTiger.com chief executive Prakash Tejwani said the numbers point to a market that is stabilising rather than slowing down. “Q2 2026 confirms India’s residential market is maturing, not weakening,” he said, noting that prices have held above ₹10,000 per square foot for two straight quarters even as buyers turn more selective. He pointed to Kolkata and Chennai as showing “genuine demand-led recovery,” while Bengaluru and Pune “continue to command pricing power despite tech-sector caution.” Sanjeevini Group chairman and founder Umesh Gowda H A said Bengaluru’s market “continues to remain resilient despite a broader moderation in housing activity across India,” describing the softer sales as “a more measured pace of absorption rather than a weakening of the market.”
POLICY TAILWINDS: STABLE RATES AND GST RELIEF
The pricing resilience comes against a backdrop of supportive government and central bank policy. The Reserve Bank of India has held its repo rate steady at 5.25%, keeping home loan borrowing costs predictable for buyers. Separately, the GST Council’s rate rationalisation earlier this year cut the tax on cement from 28% to 18% and on marble and granite from 12% to 5%, a change industry estimates suggest could offset construction costs by roughly 2–3%, offering developers some cushion against rising input and land prices even as it has yet to meaningfully lower end prices for buyers.
WHAT TO WATCH NEXT
With disciplined new supply and inventory levels still under control, developers are heading into the festive quarter — traditionally India’s strongest home-buying season around Navratri and Diwali — with pricing power intact. Analysts say affordability will remain the key variable to watch through the rest of 2026: whether launch volumes convert into fresh sales once festive-season promotions and offers begin, and whether the GST-driven cost relief eventually filters through to more competitively priced units for first-time buyers in India’s price-sensitive mid-income segment.
AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
Mumbai, September 13, 2026 — Maharashtra has laid out its most ambitious real estate and infrastructure roadmap yet, positioning the Mumbai Metropolitan Region (MMR) to become a $1.5-trillion economy by 2047 through a combination of global private capital, mega-infrastructure projects and an aggressive push to redevelop the city’s ageing housing stock.
The vision — branded “Mumbai 3.0” — has been built out in stages over the past several weeks. It began on August 7, when the Mumbai Metropolitan Region Development Authority (MMRDA) signed a set of memoranda of understanding with three Singapore-headquartered firms: Temasek Holdings, Mapletree and Surbana Jurong. Under one of these agreements, with the Raigad Pen Growth Center Limited (RPGCL), Mapletree committed to more than $1.1 billion in foreign direct investment to build a 100-acre mixed-use development within the Raigad-Pen Growth Center. Surbana Jurong, which had already authored the master and infrastructure plans for that growth centre, was appointed project management consultant for its execution.
Chief Minister Devendra Fadnavis said the talks that produced the agreements were first initiated at the World Economic Forum in Davos. “The MMR strategy is translating from planning into ground reality. With physical infrastructure work actively underway, global investors are demonstrating immense confidence in Maharashtra,” he said, adding that “Singapore’s extensive experience in master planning and urban development will significantly benefit the state.” A comprehensive master plan spanning 324 square kilometres is now meant to guide the area’s development — covering land use, transit, housing and industrial corridors — anchored by the under-construction Navi Mumbai International Airport and the Atal Setu sea bridge. State officials describe the long-term goal as knitting these together into a “Third Mumbai,” with a “Fourth Mumbai” envisioned beyond that.
The state government expanded on the plan on September 4 at the sixth edition of the Real Estate & Infrastructure Investors’ Summit (REIIS 2026) in Mumbai, where Fadnavis told developers that “Mumbai 3.0 is not a future. It has already begun.” He pointed to August 2026 property registration data — roughly 12,500 registrations in Mumbai for the month, among the highest on record — with cumulative registrations for the year crossing 1.06 lakh and generating close to ₹9,355 crore in government revenue.
On housing, the chief minister said the government’s “cluster approach” to redevelopment would make Mumbai slum-free within a decade. “The Government worked with the developers’ fraternity and today Maharashtra has the most successful regulator in India. The trade has been cleaned up and a level playing field has been created,” he said, citing MahaRERA. For the long-delayed Dharavi redevelopment project specifically, the government has set a target of handing over keys to 10,000 rehabilitation homes by January 2029.
The infrastructure list attached to the vision is extensive: a proposed 24-km Uttan–Virar sea link intended to give Mumbai signal-free connectivity from Nariman Point to Virar; a third Mumbai airport planned near Virar, with a detailed project report expected by the end of this year; and expansion of the Vadhavan deep-draft port in Palghar, which the state hopes will rank among the world’s leading ports and anchor a new freight corridor running through Nashik and the Samruddhi Mahamarg toward Jalna, Wardha and Gadchiroli. A separate initiative under Transport Minister Pratap Sarnaik — cleared by the state cabinet on July 14 — will invite tenders within three months to redevelop 140 State Transport bus depots into mixed-use “Bus Ports,” potentially unlocking 13,000-14,000 acres of MSRTC land for private development.
Fadnavis also framed the plan in demographic and technological terms, noting that roughly 65% of India’s population is young and that Maharashtra alone has close to 3 crore residents between the ages of 18 and 28. “In the next 1,000 days, the nature of 70% of jobs will change because of AI. This is an era of disruption,” he said, positioning the Mumbai-Pune corridor as a future “Quantum Corridor” for technology and global capability centres.
For an MMR real estate market still digesting the RERA decriminalisation, self-redevelopment reforms and stalled-project rescue funds that have dominated headlines this year, Mumbai 3.0 represents a shift in scale — from fixing what exists to building an entirely new economic geography around it. Whether the ₹9,355-crore registration windfall and the Singapore FDI commitments translate into delivered infrastructure on the stated timelines will be the test developers, homebuyers and investors will be watching most closely over the next few years.

By AI-Powered PMC Akbar Jiwani | Special Correspondent – Real Estate, RealNewsofIndia.com
India’s office real estate market has crossed a new institutional milestone, with the operational portfolio of listed office Real Estate Investment Trusts (REITs) surging 74 per cent year-on-year to touch 167 million square feet in the first half of 2026, up from 95.8 million square feet in the same period last year. The figures, published this week in a joint report by ASSOCHAM and Knight Frank India, show that REIT-held office space now accounts for 16 per cent of the country’s total office stock of 1.05 billion square feet — a sharp jump that underlines how quickly institutional capital is consolidating its hold on India’s commercial property landscape.
An additional 36 million square feet of office space currently under construction is earmarked for REIT platforms, indicating that the pace of institutionalisation is set to continue well into 2027 as developers increasingly package Grade-A office assets for listing rather than holding them on private balance sheets.
Bengaluru continues to lead the REIT wave by a wide margin, with 67.6 million square feet of REIT-backed office stock making up 27 per cent of the city’s total office inventory — comfortably the highest penetration of any Indian market. Hyderabad follows with 26.2 million square feet, or 20 per cent of its office stock, while Mumbai rounds out the top three with 24.6 million square feet, representing 14 per cent of the city’s inventory. The concentration in these three markets reflects sustained demand from global capability centres (GCCs) and technology occupiers, who have anchored much of the leasing activity behind REIT-grade buildings.
The institutionalisation story is no longer confined to office space. Retail REITs, led by Nexus (10.7 million square feet) and Brookfield (0.4 million square feet), now hold a combined 11 million square feet of operational mall and retail space. Notably, nearly 45 per cent of this retail REIT footprint sits outside India’s eight major metro office markets, spread across cities such as Chandigarh, Bhubaneswar, Amritsar, Udaipur, Mangaluru, Mysuru, Indore and Ludhiana — a sign that institutional ownership is beginning to reach deep into India’s tier-II consumption centres, not just its traditional commercial hubs.
A third and comparatively newer vehicle, the Warehousing Infrastructure Investment Trust (InvIT), has also gained scale, with its portfolio reaching 44.2 million square feet as of June 2026, reinforcing warehousing and logistics as the next frontier for India’s institutional real estate ecosystem.
Commenting on the findings, Shishir Baijal, International Partner, Chairman and Managing Director of Knight Frank India, said the expansion of retail REITs was “widening the geographic footprint of institutional real estate ownership beyond the established office markets,” pointing to a structural broadening of India’s REIT story beyond the usual metro-centric narrative.
On the regulatory front, Parneet S. Sachde, Chairman of the Real Estate Regulatory Authority, offered a broader reflection on where India’s real estate governance framework must head next, noting that “the first decade created a statutory architecture of trust. The second decade must create a technological architecture of trust” — a remark widely read as a call for greater digitisation and transparency in property regulation as the sector matures.
Taken together, the numbers point to a real estate market that is steadily shifting from fragmented private ownership toward listed, professionally managed platforms — a trend that analysts say improves transparency for investors, deepens capital markets, and gives retail investors direct exposure to India’s commercial property growth story. With 36 million square feet of fresh office supply in the REIT pipeline and warehousing InvITs gaining traction, India’s institutional real estate footprint appears poised for further expansion through the rest of 2026.






Recent Comments