



By Ai Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
Mumbai/New Delhi: India’s housing market held its ground in the first nine months of 2026. Eight major cities recorded 2,58,238 home sales between January and September, roughly flat on last year, according to Knight Frank India data released on 5 October. The data shows buyers moving steadily towards higher-priced homes, while the entry-level segment weakens.
Mumbai leads, Bengaluru grows fastest among the big markets
The seven markets outside the National Capital Region grew 2% together. Mumbai stayed the largest market with 72,804 sales, up 1%. Bengaluru recorded 43,140 sales, up 5%. Pune was roughly flat at 36,402 units. Hyderabad, Ahmedabad, Chennai and Kolkata each grew between 2% and 4%.
NCR the weak spot
NCR sold 35,574 homes, down 11%. Sales in the ₹5–10 crore band fell 39% to 4,033 units. Gurugram accounts for 57% of the region’s unsold inventory.
Premium homes take a bigger share
Homes priced above ₹1 crore made up 55% of all sales, up from 50% a year ago. The ₹1–2 crore bracket was the largest segment at 77,087 units, up 6.8%. The ₹2–5 crore segment grew 19.4% to 51,501 units, with Chennai posting 54% growth in that range. Sales in the ₹50 lakh–1 crore band fell 5.9% to 69,380 units. Homes below ₹50 lakh fell 14% to 47,660 units, and their share dropped to 18%.
Supply keeps outpacing demand
Developers launched 2,79,899 homes in the nine months, up 4%. Third-quarter launches were 92,549, also up 4%. New supply has exceeded sales for 16 consecutive quarters, and inventory overhang has edged up to 6.1 quarters. Prices rose between 3% and 17% across markets.
Knight Frank India chairman Shishir Baijal described the trend as “normalisation rather than a widespread slowdown.” He said income growth, suitable supply and local demand will increasingly decide how each market performs as the benefits of lower interest rates moderate.
Government relief for developers
Separately, the Ministry of Housing and Urban Affairs on 31 July advised state RERAs to extend registration and completion timelines by four months for projects with deadlines falling on or after 28 February 2026. The advisory cites supply-chain disruption from the West Asia conflict, which the finance ministry declared a force majeure event on 29 April. It also asks RERAs to issue a common order so developers need not file project-wise applications. CREDAI president Shekhar Patel called it “a positive step taken in line with the sector’s demand.”
Outlook: Steady volumes, rising prices and a shrinking affordable share point to a market growing in value rather than volume. Affordability for first-time buyers remains the key concern for policymakers and developers
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate for Realnewsofindia.com
New Delhi/Mumbai, 10 October 2026: India’s housing market has entered the festive season with two developments pulling in different directions. Sales are at a healthy quarterly high, while the Reserve Bank of India (RBI) has raised interest rates for the first time in almost four years.
RBI turns to “calibrated tightening”
On 7 October the RBI’s Monetary Policy Committee raised the repo rate by 25 basis points to 5.5%. This is the first hike since February 2023. The committee also changed its stance from “neutral” to “calibrated tightening”. The rate decision was unanimous, but the stance change passed 4–2.
The central bank cited consumer inflation of 4.8% in August, above its 4% target for a third straight month. It also pointed to volatile crude oil prices linked to renewed US–Iran tensions. It raised its full-year inflation forecast to 5.2% from 5%. It projects GDP growth of 7.1% for the year, after 7.8% growth in the April–June quarter.
What it means for home buyers
More than 68% of floating-rate rupee loans at scheduled commercial banks are linked to external benchmarks that track the repo rate. At private banks the share is above 90%. Floating-rate home loan borrowers can therefore expect a 25 bps rise in rates, which means a higher EMI or a longer loan tenure. Fixed-rate loans will not change immediately but will reprice when their lock-in periods end.
Anuj Puri, Chairman of ANAROCK Group, warned that “even a modest increase in EMIs will result in deferred purchase decisions” among affordable housing buyers. He said commercial real estate is unlikely to see a direct impact, though some new mall projects “could potentially be deferred until there is greater clarity on demand.”
Developers were divided. Ramani Sastri, MD of Sterling Developers, said the hike “would definitely impact housing affordability” and could bring a short-term dip in demand. Rayan Munawer, CEO of Terray Realty, said he does not expect the increase alone to significantly disrupt housing demand. JLL’s Lata Pillai described the move as pre-emptive, aimed at inflation peaks later in the year.
Q3 numbers show a resilient market
The timing matters because the market came into the hike on solid footing. ANAROCK data for July–September 2026 shows the following for the top seven cities:
Sales: about 1,00,220 units, up 3% from 97,080 a year earlier. Sales value was about ₹1.55 lakh crore, up 2%.
New launches: about 1,14,320 units, up 18% from 96,690.
Prices: average residential prices rose 7% year on year. The NCR rose 12% and Bengaluru 8%.
Unsold inventory: about 6.31 lakh units, up 12% from about 5.62 lakh.
City trends varied widely. The Mumbai Metropolitan Region sold about 31,750 units (+5%), Bengaluru 16,670 (+12%) and Hyderabad about 12,970 (+15%, the fastest growth). Pune (−6%), NCR (−1%), Kolkata (−4%) and Chennai (−10%) declined. MMR and Bengaluru together made up 48% of sales.
Hyderabad’s launches more than doubled (+120%) to about 18,950 units. By price band, 34% of new launches were in the ₹80 lakh–₹1.5 crore range and 24% in ₹1.5–2.5 crore. Only 14% were priced below ₹40 lakh. This shows how thin the supply of entry-level homes remains.
The road ahead
Rising inventory, higher prices and costlier loans together mean buyers are likely to stay selective. Analysts say the pace of any further rate action will matter more than this single hike. Developers are expected to lean on festive-season offers and flexible payment plans over the coming weeks. Home buyers are advised to check how their lender’s rate reset works, and to compare fixed and floating options before committing.
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate for Realnewsofindia.com
MUMBAI/NEW DELHI, 9 October 2026: India’s residential market entered the festive season with modest sales growth and a sharp rise in new supply. Property consultant Anarock’s Q3 2026 report (published 2 October) shows housing sales in the top seven cities rose 3% year-on-year to about 1,00,220 units in July-September, from 97,080 units a year earlier. Sales value rose 2% to about Rs 1.55 lakh crore.
Launches surge. New launches rose 18% to about 1,14,320 units, from 96,690 units in Q3 2025. Mumbai Metropolitan Region (MMR), Pune, Bengaluru and Hyderabad accounted for 81% of new supply. By price band, Rs 80 lakh to Rs 1.5 crore homes made up 34% of launches, Rs 1.5 to 2.5 crore 24%, Rs 40 to 80 lakh 17% and homes below Rs 40 lakh 14%.
Prices and inventory. Average residential prices rose 7% year-on-year, with NCR recording the steepest appreciation at 12%, followed by Bengaluru at 8%. Unsold inventory rose 12% to about 6.31 lakh units, from about 5.62 lakh units a year ago, as supply outpaced absorption.
City-wise picture. Hyderabad was the standout, with sales up 15% to 12,970 units and launches more than doubling (+120%) to 18,950 units. Bengaluru sales rose 12% to 16,670 units. MMR, the largest market, sold 31,750 units (+5%), and together with Bengaluru accounted for 48% of total sales. Pune fell 6% to 15,690 units, NCR dipped 1% to 13,765 units, Kolkata slipped 4% and Chennai declined 10%.
Another view. PropEquity’s report (1 October), covering the top nine cities, recorded 1,03,170 units sold in Q3, down 6% year-on-year and 4% from the previous quarter, with launches down 2% year-on-year and 15% quarter-on-quarter. It showed Hyderabad up 11%, Bengaluru up 1%, Mumbai down 8%, Thane down 11%, Pune down 16% and Chennai down 17%. PropEquity founder and CEO Samir Jasuja noted that absorption fell only 4% despite a sharp drop in supply, keeping the demand-supply balance steady, and linked slower launches to developers’ caution while they manage existing inventory. The two firms cover different city sets and define markets differently, so analysts advise comparing trends rather than totals; both agree on Hyderabad’s strength and weakness in Pune and Chennai.
Outlook. Anarock chairman Anuj Puri said buyers may remain selective because of higher property prices and affordability concerns, but expects the festive period to be supported by stable borrowing costs and new launches. With inventory building up, homebuyers may see more discounts, festive offers and flexible payment plans, while developers are likely to focus on mid-premium and premium segments where demand is steadier.
Sources: Anarock Q3 2026 report via PropNewsTime (2 Oct 2026); PropEquity Q3 2026 report via Grihik (1 Oct 2026). Figures are as reported by the research firms.
By Ai Powered PMC Akbar Jiwani
Special Correspondent: Real Estate
SUB-HEADLINE: First rate hike since February 2023 puts home loan EMIs under watch just as the festive season begins; commercial real estate largely insulated, retail more exposed
Mumbai, 8 October 2026: The Reserve Bank of India’s Monetary Policy Committee raised the repo rate by 25 basis points, from 5.25% to 5.50%, on 7 October 2026, ending a run of four consecutive holds. It is the first hike since February 2023, and the central bank has moved its stance to “calibrated tightening”. Analysts now see a pause or a further hike as more likely than a cut in coming meetings, which matters directly for India’s housing market at the start of the festive buying season.
WHY THE RBI MOVED
Reports cite inflation pressure from an El Niño-hit monsoon, rising energy costs, Gulf-related geopolitical uncertainty, tightening by global central banks, rupee weakness and higher crude prices. The economy itself remains strong: Q1 FY27 GDP grew 7.8%, and the RBI has raised its FY27 growth forecast to 7.1%. Lata Pillai, Head of Capital Markets, India, at JLL, described the move as “a pre-emptive measure to account for further inflation peaks later in the year”, citing projected CPI inflation of 5.2% this year and 5.7% next year.
WHAT IT MEANS FOR HOME LOAN BORROWERS
Entry-level home loan rates are around 7.1% to 7.75%, though many borrowers pay roughly 8% to 9.8%, according to Anarock. Floating-rate loans are expected to be repriced. Mehernosh Tata of Godrej Housing Finance said the hike “could mean a higher EMI, a longer loan tenure, or a combination of the two”, depending on loan structure and how the change is passed on.
AFFORDABLE AND MID-INCOME HOUSING MOST SENSITIVE
The most price-sensitive buyers are in affordable homes (under Rs 75 lakh) and mid-income homes (Rs 75 lakh to Rs 2 crore). Anuj Puri, Chairman of the ANAROCK Group, warned that “even a modest increase in EMIs will result in deferred purchase decisions” among affordable-housing buyers. Average residential prices in the top seven cities have already risen about 7% year-on-year in Q3 2026, stretching affordability further. Experts also expect some construction cost increases to be passed on to buyers.
Shekhar Patel of CREDAI said the increase in borrowing costs “could have some impact on sales during this period”, referring to the festive season. Pradeep Aggarwal of Signature Global noted that “a stable repo rate would have better sustained the current demand momentum.”
DEMAND FUNDAMENTALS REMAIN STRONG
Anarock data shows about 100,220 homes were sold in the top seven cities in Q3 2026, up 3% year-on-year and 10% quarter-on-quarter. Affordable housing accounted for 16% of those sales. Shishir Baijal of Knight Frank India expects affordability pressure in lower-priced segments but no major near-term disruption, backed by GDP growth, investment and construction activity.
COMMERCIAL AND RETAIL
Commercial real estate is unlikely to be directly affected, given steady demand from GCCs, technology, BFSI and other occupiers. Retail is more exposed: Puri said “some new mall projects could potentially be deferred until there is greater clarity on demand.” Real estate investment funds may also face higher project financing costs and become more selective, according to Ankur Jalan of Golden Growth Fund.
OUTLOOK
Industry voices agree the pace of future moves will matter more than this single hike. Anshuman Magazine of CBRE said the key question is “whether this increase stays a calibrated response rather than the start of a long tightening cycle.” Buyers are advised to review loan terms, compare lender offers and plan finances carefully before committing during the festive period.
Sources: Business Standard (7 Oct 2026, “RBI rate hike may pressure housing affordability, but demand seen resilient”); The Week (7 Oct 2026, “Mixed bag: How experts diverged in their reaction to RBI raising repo rate”).
By AI-Powered PMC Akbar Jiwani
Special Correspondent: Real Estate, for Realnewsofindia.com
HEADLINE:
Centre Asks State RERAs to Extend Realty Project Deadlines by Four Months, Cites West Asia Conflict as Force Majeure
SUB-HEADLINE:
Housing Ministry advisory spares developers from filing individual extension applications; homebuyers’ interests to be protected through orderly execution
BODY:
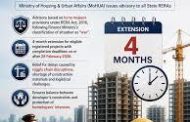
NEW DELHI: In a significant relief measure for India’s real estate sector, the Ministry of Housing and Urban Affairs (MoHUA) has advised state Real Estate Regulatory Authorities (RERAs) to extend the registration and completion timelines of ongoing projects by four months.
The advisory applies to projects whose completion dates fall on or after 28 February 2026. Crucially, developers will not need to file separate extension applications for each project, cutting down paperwork and delays for thousands of builders across the country.
Force majeure under the RERA Act
The ministry has based the move on the West Asia conflict, which the finance ministry declared a force majeure event on 29 April 2026. The conflict has caused global supply chain disruptions, shortages of construction materials and difficulties in labour availability, all of which have slowed construction activity in India.
Industry welcomes the move
Developers’ body CREDAI welcomed the advisory. CREDAI President Shekhar Patel said the extension “will help developers align project completion timelines with the current market scenario while relieving them of the unnecessary burden of filing separate applications.”
What it means for homebuyers
While the extension gives builders breathing room, the ministry has stressed that the interests of homebuyers must remain protected through orderly project execution. Buyers of projects covered by the advisory should note that the revised timelines are expected to be applied by the respective state RERAs, and should check their state RERA’s notification for specifics.
What it means for developers
The blanket extension removes the compliance burden of individual applications, helps avoid penalties linked to missed deadlines caused by external disruptions, and lets developers plan delivery schedules more realistically in a tough cost environment.
Also on the radar: RBI policy and festive demand
The advisory comes as the sector watches the Reserve Bank of India’s October monetary policy review, with the repo rate at 5.25% after four consecutive holds. Retail inflation rose to 4.82% in August, and several economists had anticipated a possible 25 bps hike. Developers say rate stability is key to sustaining festive-season housing demand, particularly among first-time and mid-income buyers.
The Centre’s advisory underlines the government’s effort to keep project delivery on track and sustain confidence in the housing market a
Written by AI Powered PMC Akbar Jiwani
Special Correspondent: Real Estate, for Realnewsofindia.com
Knight Frank says launches have outpaced sales for 16 straight quarters; homes above ₹1 crore now make up 55% of sales
Mumbai/New Delhi, 6 October 2026: India’s housing market is moving into what industry experts call a more selective phase. Sales in the top eight cities were flat over the first nine months of calendar year 2026, while buyers kept shifting towards higher-priced homes, according to the latest report from property consultant Knight Frank India, released on 5 October.
Sales in the January-September period were 2,58,238 units, flat from a year earlier. New launches rose 4% year-on-year to 2,79,899 units. Launches have now exceeded sales for 16 consecutive quarters. In the July-September quarter alone, sales were 86,767 units (down 1% year-on-year) and launches were 92,549 units (up 4%).
City-wise picture
Mumbai remained the largest market with 72,804 units sold, up 1%. Bengaluru recorded 43,140 units, up 5%. Pune was flat at 36,402 units. The National Capital Region was the weakest, at 35,574 units, down 11%. Hyderabad, Ahmedabad, Chennai and Kolkata saw growth of roughly 2% to 4%.
Premium homes gain, affordable segment shrinks
Homes priced at ₹1 crore and above accounted for 55% of all sales, up from 50% a year earlier. The ₹1-2 crore bracket made up 30% of sales (77,087 units, up 6.8%), while the ₹2-5 crore segment rose 19.4% to 51,501 units. Sales of homes below ₹50 lakh fell 14% to 47,660 units, and their share dropped to 18%.
Inventory and prices
The time needed to sell existing unsold stock (quarters-to-sell) rose to 6.1 quarters in Q3 2026 from 5.8 a year earlier. Prices rose 3-6% year-on-year in most markets, while Bengaluru led with an 11% increase.
“India’s residential market is entering a more discerning phase, in which the quality and relevance of supply will matter,” said Shishir Baijal of Knight Frank India.
Note: Other trackers show slightly different numbers. Anarock reported a 3% rise in Q3 sales across the top seven cities, with launches up 18%. The difference comes from varying city coverage and methodology.
All eyes on the RBI
The sector now awaits the Reserve Bank of India’s Monetary Policy Committee decision on 7 October. The repo rate stands at 5.25%, and many economists expect a 25 basis point hike to 5.50%, which would be the first increase since February 2023. Retail inflation rose to 4.82% in August, above the RBI’s 4% target for the third straight month, partly due to higher crude oil prices and global bond yields.
For a floating-rate borrower, the effect is modest but real. On a ₹50 lakh, 20-year loan at 8.50%, the EMI is about ₹43,400. A 25 bps increase to 8.75% would raise it to about ₹44,200, roughly ₹800 more per month.
Industry voices say a rate hike does not automatically push prices down, but it may slow transactions first, particularly in affordable and mid-income segments, which are more sensitive to financing costs than luxury buyers. Developers may respond with incentives and payment plans instead of cutting quoted prices. Analysts add that markets with strong employment and infrastructure, such as Bengaluru, Hyderabad and Mumbai, are likely to remain more resilient.
What it means
With flat volumes, rising unsold inventory timelines and a possible rate hike, developers are expected to focus on better-located, well-priced and timely-delivered projects. Homebuyers are advised to compare loan offers and check RERA registration before committing.
Written by Ai Powered PMC Akbar Jiwani
Special Correspondent: Real Estate, for Realnewsofindia.com
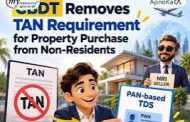
New Delhi, 5 October 2026: Resident Indians buying a house, flat or plot from a Non-Resident Indian (NRI) have just got a significant compliance relief. Under changes that took effect on 1 October 2026, resident individual and Hindu Undivided Family (HUF) buyers can now deduct and deposit tax on such purchases using only their Permanent Account Number (PAN), without having to first obtain a Tax Deduction and Collection Account Number (TAN).
What has changed
Earlier, a buyer purchasing immovable property from a non-resident seller had to obtain a TAN, deduct tax at source, deposit it and file statements, a procedure many first-time and individual buyers found cumbersome and a common cause of delayed registrations and notices. Under the revised framework notified by the Central Board of Direct Taxes (CBDT), reporting is consolidated through Form 141 (Challan-cum-Statement of Deduction of Tax), which replaces multiple earlier forms.
Who benefits
The relief applies to resident individuals and HUFs buying property from NRIs. Companies and firms purchasing from non-residents will continue to require a TAN.
Tax rates remain unchanged
The simplification concerns procedure, not the tax burden. For non-resident sellers, TDS applies on the capital gains element: 12.5% (plus applicable surcharge and cess) on long-term gains where the property was held for more than 24 months, and at applicable slab rates, up to 30% plus surcharge and cess, on short-term gains. The Rs 50 lakh threshold and 1% TDS rate that apply to resident sellers do not apply when the seller is a non-resident.
Why it matters for real estate
NRIs are a major buyer and seller segment, particularly in Gujarat, Kerala, Punjab, Telangana, Maharashtra and the metro markets. Easier compliance for the resident counterparty should reduce friction in resale transactions, shorten closing timelines and lower the risk of post-registration tax notices. Industry observers expect the change to support sentiment in the secondary market just as the festive season begins, a period that traditionally lifts housing demand. The move also fits the government’s broader emphasis on ease of doing business and transparent, technology-enabled tax administration.
What buyers should do
Buyers should still deduct the correct tax from the sale consideration, deposit it through Form 141 within the prescribed time, and keep the challan as proof. Sellers should obtain the TDS record to claim credit while filing returns. Because the capital gains computation can be complex, both parties are advised to consult a qualified chartered accountant before closing a deal.
Sources: Outlook Money, CAclubindia, A2Z Taxcorp, Pune Pulse, Inkl (reports on CBDT notification, effective 1 October 2026). Please verify figures against the official CBDT notification before publishing.
By Ai Powered PMC Akbar Jiwani
Special Correspondent: Realestate for Realnewsofindia.com
MUMBAI/NEW DELHI: The Mumbai Metropolitan Region (MMR) has overtaken the National Capital Region (NCR) to become India’s largest housing market, even as overall residential sales value across the country plateaued in the first half of 2026, according to the India Housing Report (January-June 2026) prepared by CRE Matrix and the National Association of Realtors-India.
THE NATIONAL PICTURE
Housing sales value in H1 2026 stood at Rs 3.63 lakh crore, virtually flat against the same period last year. Units sold came in at about 2.58 lakh homes, a 2% year-on-year decline. Developers, however, remain confident: new launches rose 7% to roughly 2.98 lakh units. The average ticket size rose just 2% to about Rs 1.4 crore, the slowest rise in three years, indicating that the sharp price-led growth of recent years is cooling.
MMR TAKES THE LEAD
MMR now accounts for 26% of national sales value against NCR’s 19%. MMR recorded sales of Rs 93,800 crore (up 8%) across 83,600 units at an average ticket size of Rs 1.12 crore. Within the region, Mumbai city posted Rs 58,362 crore (up 4%), while Navi Mumbai-Raigad grew 29% to Rs 12,292 crore on the back of affordable inventory averaging Rs 71 lakh per unit.
BENGALURU AND SOUTH GAIN
Bengaluru was the standout performer, with sales value up 25% to Rs 60,875 crore across 34,600 units. The Rs 2-5 crore bracket rose from 32% to 41% of the city’s sales value, showing deepening demand for premium housing. Chennai grew 16% to Rs 13,722 crore, while Hyderabad was flat at Rs 56,966 crore.
NCR CORRECTS
NCR’s sales value fell 24% to Rs 68,217 crore across 24,600 units, with an average ticket of Rs 2.77 crore. The luxury segment saw a visible correction in Gurugram, where homes priced above Rs 5 crore fell from 66% to 52% of sales value.
POLICY WATCH: NEW TDS REPORTING RULES FROM 1 OCTOBER
Separately, new reporting rules for tax deducted on property purchases from non-resident sellers took effect on 1 October 2026. Resident individuals and HUFs buying from an NRI can now use their PAN instead of obtaining a TAN, while companies and firms must still hold a TAN. TDS rates remain 12.5% on long-term gains (held 24 months or more) and slab rates up to 30% on short-term gains, plus applicable surcharge and cess. Compliance is consolidated into Form 141. The Rs 50 lakh threshold does not apply to non-resident sellers.
WHAT IT MEANS
Analysts note the shift reflects buyers moving toward well-connected, infrastructure-led markets and mid-premium homes, while NCR’s luxury segment recalibrates. With launches rising faster than sales, developers may need sharper pricing and delivery credibility to sustain momentum in the festive season.
Sources: Business Standard (India’s housing market hits plateau: Sales flat at Rs 3.6 lakh cr in H1 2026, 28 Sep 2026) – https://www.google.com/url?q=https://business-standard.com/finance/personal-finance/india-s-housing-market-hits-plateau-sales-flat-at-3-6-lakh-cr-in-h1-2026-126092800084_1.html&source=gmail&ust=1791164633014000&sa=E ; CAclubindia (TDS on Purchase of Property: New Reporting Rules from 1st October 2026) – https://www.google.com/url?q=https://www.caclubindia.com/articles/tds-on-purchase-of-property-new-reporting-rules-from-1st-october-2026-56315.asp&source=gmail&ust=1791164633014000&sa=E

Written by Ai Powered PMC Akbar Jiwani
Special Correspondent: Realestate for Realnewsofindia.com
BMC’s first phase of the Rs 14,000-crore GMLR project is in its final finishing stage; analysts expect a lasting boost to micro-markets between Goregaon and Mulund
Mumbai, 3 October 2026 – Mumbai’s long-awaited Goregaon–Mulund Link Road (GMLR) is about to reach its first big milestone. The Brihanmumbai Municipal Corporation (BMC) is targeting October 15, 2026 for opening the Dindoshi–Film City flyover, a roughly 1.2–1.3 km, six-lane elevated stretch that will directly link the Western Express Highway at Dindoshi with Film City in Goregaon East.
According to project updates, the main civil work is complete, including all 31 piers, 30 spans, girders and deck slab. Finishing work is under way: road markings, signage, electrical poles, noise barriers, slip roads and traffic-management arrangements. A load test is planned for the second week of October. The flyover, reported to cost about Rs 300 crore, missed earlier deadlines of May and September 2026.
Why the flyover matters
The flyover is the first operational piece of the 12.2-km GMLR, a project estimated at around Rs 14,000 crore that will connect the Western Express Highway with the Eastern Express Highway. The full corridor includes twin tunnels beneath Sanjay Gandhi National Park and between the Tulsi and Vihar lakes, which are expected to open by 2027. Officials say the completed link could cut east–west travel time between the suburbs from about 75 minutes to around 25 minutes.
What it means for real estate
Infrastructure has long been the strongest driver of micro-market growth in the Mumbai Metropolitan Region, and the GMLR is no exception. Localities such as Goregaon East, Dindoshi, Malad East, Powai, Vikhroli, Bhandup and Mulund are seen as the main beneficiaries. Market commentary cited by property portals suggests that corridor values could rise by 12% to 20% over the next 24 to 36 months as connectivity improves. This is an analyst projection, not a guarantee, and actual gains will vary by project and location.
The timing is significant. Anarock data released on September 28 showed housing sales in India’s top seven cities rose 3% year-on-year to about 100,220 units in the July–September quarter, with new launches up 18% to about 114,320 units. The MMR led all cities with roughly 31,750 units sold. Developers are likely to use improved connectivity as a selling point during the upcoming festive season.
What buyers should keep in mind
Buyers should check RERA registration, project timelines and the actual commissioning status of the corridor before committing. Early price gains often reflect expectations, and the full benefit will only be visible once the twin tunnels are operational.
Opening dates for large civil projects can shift, so the October 15 target should be treated as provisional until the BMC makes an official announcement.
By Ai Powered PMC Akbar Jiwani
Special Correspondent: Real Estate, for Realnewsofindia.com
MUMBAI / NEW DELHI, October 2, 2026: India’s housing market enters its most important selling window of the year with one big question hanging over it: will the Reserve Bank of India change interest rates? The central bank’s Monetary Policy Committee (MPC) meets from October 5 to 7, just as the Navratri and Diwali festive season gathers pace, and the outcome could shape home-loan costs and buyer sentiment for the rest of the financial year.
WHERE RATES STAND
The repo rate is currently 5.25%, unchanged since August 2026. Retail inflation (CPI) rose to 4.82% in August from 4.45% in July, its fourth consecutive monthly increase, with food inflation at 5.95%. Brent crude is trading near $107 a barrel, the rupee is weak at around 96 to the US dollar, and foreign investors pulled out about $3.7 billion in September, according to market reports.
Market commentary is divided. Some reports expect the RBI to hold rates and retain its neutral stance, keeping “all options open”, while others flag the risk of a 25 basis point hike to 5.50%. Nothing is certain until the MPC announces its decision.
WHAT IT MEANS FOR HOMEBUYERS
Most home loans in India are linked to the repo rate, so a hike would feed into floating-rate EMIs, usually with a lag. As an illustration, on a Rs 50 lakh, 20-year loan, a 0.25 percentage point rise (for example from 8.50% to 8.75%) would add roughly Rs 790 to the monthly EMI. If rates are held, EMIs should remain largely stable. Analysts note that price-sensitive buyers are most likely to pause or re-think timelines if borrowing costs rise.
WHY THE TIMING MATTERS
The festive season traditionally brings the year’s highest bookings, as buyers see Navratri and Diwali as auspicious. Demand has been resilient but selective: according to Anarock data released on October 1, sales across the top seven cities rose 3% year-on-year to 100,220 units in Q3 2026, ending three consecutive quarters of decline, while new launches jumped 18% to 114,320 units. Average prices rose 7% to Rs 9,714 per sq ft and unsold inventory stands at about 6.3 lakh units. Anarock noted that buyers are becoming more selective as prices rise. PropEquity’s tracker, using a different methodology, showed a 6% decline, a reminder that data providers differ.
THE DEVELOPER VIEW
Higher rates raise the cost of servicing debt and funding construction, which can squeeze margins for developers who cannot pass on costs. Institutional investment into Indian real estate was reported at around $9.5 billion in Q3 2026, indicating that long-term capital remains confident in the sector despite near-term uncertainty.
POLICY SUPPORT IN THE BACKGROUND
On the government side, the allocation for PMAY-Urban has been raised sharply to Rs 22,025 crore in FY27, and several states have cut stamp duty and registration charges for homes built under the scheme. Industry bodies such as NAREDCO, in a KPMG-NAREDCO report, continue to press for affordable housing incentives, formal rental housing and tighter RERA-IBC coordination. Affordable housing has fallen to just 6% of new launches in Q2 2026, according to industry data, which is why such support is closely watched.
WHAT TO WATCH
Buyers should keep an eye on the MPC statement on October 7, on how banks pass on any change, and on developer festive offers. Experts generally advise buyers to budget for a modest rise in EMIs, compare lenders’ rates, and avoid stretching their EMI-to-income ratio.
Disclaimer: This article is for information only and is not financial or investment advice. Rate expectations are based on media reports and may change after the RBI’s announcement. EMI figures are illustrative.






Recent Comments