
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
Published: 19 October 2026
JAIPUR: Rajasthan Chief Minister Bhajan Lal Sharma on 17 October 2026 launched four housing projects of the Rajasthan Housing Board (RHB), adding 457 homes to the state’s residential supply across Jaipur, Kishangarh and Bhiwadi.
The launch took place at the Constitution Club in Jaipur. Urban Development and Housing Minister Jhabar Singh Khara and Jaipur Mayor Sunil Kothari were present.
What has been launched
Jaipur, Jagatpura (Sector 9), Indira Gandhi Nagar scheme: 144 MIG-B flats reserved for journalists.
Jaipur, Pratap Nagar: 146 units in the next phase of Greenwood Horizon.
Kishangarh, Khoda Ganesh Road: 90 independent houses.
Bhiwadi, Aravali Vihar: 77 flats.
Journalist housing scheme: key details
The Jagatpura building has a basement, a stilt level and nine floors. Each flat has a built-up area of 118.38 sq m and a super built-up area of 154.639 sq m. The estimated cost is Rs 74.68 lakh per flat.
Eligible applicants are accredited, full-time journalists working in Rajasthan who depend on journalism for their livelihood, with an annual family income above Rs 3 lakh. Allotment will be by lottery, subject to eligibility conditions and income-based preferences. Prices, timelines and application dates for the other three projects were not specified in available reports.
Why it matters
The launch spreads state-backed supply across a metro, a fast-growing industrial town and a tier-2 location. The wider market is also expanding. According to Anarock data reported this week, residential launches in the top seven cities rose 18% in Q3 to 114,320 units, with developers offering festive incentives. A CII-Knight Frank study found that residential prices in 11 tier-2 and tier-3 cities grew at about 8% CAGR from 2016 to 2026, against 4% in the eight major metros. That supports demand for projects outside the big cities.
What buyers should do: Check the RHB’s official registration notices, eligibility rules and allotment procedures before applying.
Written by Ai Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
Mumbai, 17 October 2026: The Maharashtra government’s registration department has tightened the process for registering property documents presented outside the taluka where the property is located, in a move aimed at plugging stamp duty leakage and protecting buyers from legal complications.
According to a circular dated 12 October, reported this week, joint sub-registrars will now have to seek permission before registering any document that is presented outside the taluka of the property concerned. A joint district registrar has been given two days to review such cases and give a decision.
Why the change
The department’s stated aims are to curb stamp duty evasion, prevent undervaluation of properties, and reduce the risk of legal encumbrances that can surface when documents are registered away from the local jurisdiction where records and valuations are best known. Out-of-jurisdiction registrations have long been seen as a route to dodge accurate valuation checks.
RERA projects exempt
Importantly for homebuyers and developers, the new procedure does not apply to RERA-registered projects. Buyers purchasing in registered projects can therefore continue to complete registration without the additional approval step, a move that reinforces the advantage of buying in RERA-compliant developments.
What it means for buyers, sellers and developers
Resale buyers, plot purchasers and those dealing in non-RERA or older properties should factor in the extra review time of up to two days when planning registration. Legal advisers recommend keeping title documents, valuation papers and identity records complete before presenting documents, to avoid delays. For genuine transactions the impact is expected to be limited, while the check is expected to add discipline to a segment where undervaluation has been a recurring concern.
The bigger picture
The circular comes amid a wider push by states to digitise and tighten property administration, improve transparency and protect revenue. For India’s housing market, where transparency and clean titles are central to buyer confidence, such steps – alongside RERA enforcement – are seen as supporting long-term, healthy growth in the sector.
Note to editor: Details are based on published reports of the 12 October circular (e.g., Prop News Time, 16 Oct 2026); the circular text could not be independently verified at the time of writing. Please confirm with the Maharashtra Inspector General of Registration (IGR) website before publishing.
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate, for Realnewsofindia.com
New Delhi, 16 October 2026: India’s residential construction sector has grown to an estimated value of $430 billion, nearly double the $235 billion recorded in 2019, according to figures reported this week by financial news portal Whalesbook on 15 October 2026. The numbers underline how strongly housing continues to anchor the country’s real estate story.
Residential projects now make up about 85 per cent of the total value of real estate under construction in India. Including office, retail and warehousing assets, the total value of real estate projects under construction stands at around $503 billion. Warehousing, once a niche segment, has grown to roughly $10 billion by 2025, reflecting demand from e-commerce and logistics players.
A $1 trillion market by 2030
Industry projections cited in the report place India’s overall real estate market at $1 trillion by 2030, with a longer-term aspiration of $5.8 trillion by 2047. Steady leasing demand from Global Capability Centres (GCCs) is expected to continue supporting the office segment, even as housing remains the largest contributor to activity on the ground.
Risks to watch
The report also flags several factors that could temper growth. High interest and mortgage rates continue to weigh on home affordability, while rising property prices in major cities can slow sales. Compliance under the Real Estate (Regulation and Development) Act (RERA) has improved transparency for buyers but can also add to project timelines and costs. Developers, meanwhile, must manage debt carefully while funding large expansions, and fluctuating raw material costs put pressure on margins.
Analysts suggest that sales sustainability, home loan rates, developer margins, the pace of project completion and inventory levels in key urban centres are the indicators to track in the coming quarters.
Also on the regulatory front
Separately, a tax-compliance change effective 1 October 2026 is relevant for property deals involving non-resident sellers. As per secondary reports, resident individual and HUF buyers can now report and pay TDS on such purchases using their PAN instead of obtaining a TAN, while companies and firms still need a TAN. Reports indicate TDS on long-term gains from such sales is 12.5 per cent, with short-term gains taxed at applicable slab rates, and that Form 141 is used for consolidated reporting. Buyers are advised to verify details against the official Income Tax Department notification.
Outlook
With construction value having roughly doubled in just seven years, India’s property sector enters the festive season with strong fundamentals but a clear need for balance between growth, affordability and regulatory discipline. For homebuyers, investors and developers alike, project-level due diligence and RERA verification remain essential.
Sources: Whalesbook (15 Oct 2026), CAclubindia (TDS reporting rules, updated 3 Oct 2026). Figures are as reported by these outlets and are for information only; this is not investment advice. Editor: please verify figures before publishing.
Written by Ai Powered PMC Akbar Jiwani
Special Correspondent: Real Estate, for Realnewsofindia.com
Mumbai/New Delhi: India’s housing market enters the peak festive season with a new variable: costlier money. On 7 October 2026, the Reserve Bank of India’s Monetary Policy Committee raised the repo rate by 25 basis points to 5.50%, the first increase since February 2023, and moved to a “calibrated tightening” stance.
The decision lands at a delicate moment for real estate. Fresh data from property consultant Anarock shows the top seven cities recorded about 1,00,220 housing unit sales in the July-September 2026 quarter, up 3% from 97,080 units a year earlier. Sales value rose about 2% to roughly Rs 1.55 lakh crore. New launches jumped 18% to about 1,14,320 units, while average residential prices climbed 7% year-on-year.
What the rate hike means for borrowers
Floating-rate home loans linked to external benchmarks will reset at each lender’s next scheduled reset date, so the effect will be gradual. As an illustration, on a 20-year loan of Rs 50 lakh, a 25 bps rise (for example, from 8.50% to 8.75%) lifts the monthly EMI by roughly Rs 800. Some lenders may keep EMIs unchanged and stretch the tenure instead, which raises total interest paid. Fixed-rate loans are unaffected during their fixed period. LIC Housing Finance MD and CEO Sandeep Kumar said the hike “may lead to a gradual increase in borrowing costs” for the housing finance sector.
City-wise picture
Hyderabad led growth with sales up about 15% to roughly 12,970 units, followed by Bengaluru (up 12% to 16,670 units) and the Mumbai Metropolitan Region (up 5% to 31,750 units). Pune fell 6%, NCR slipped 1%, Chennai dropped 10% and Kolkata eased 4%. MMR and Bengaluru together accounted for 48% of all sales. Price growth was sharpest in NCR at 12%, followed by Bengaluru at 8%.
Supply is rising faster than demand. Unsold inventory in the seven cities stood at about 6.31 lakh units, up 12% year-on-year from about 5.62 lakh units. Launches were concentrated in the Rs 80 lakh to Rs 1.5 crore band (34%) and the Rs 1.5 crore to Rs 2.5 crore band (24%), while homes below Rs 40 lakh made up just 14% of launches, underlining the continuing squeeze on affordable housing.
Industry reaction
Developers and industry bodies broadly expect the impact to be limited. CREDAI’s Shekhar Patel said the interest rate at any given point is “only one part of a much longer decision.” Experion Developers CEO B.K. Malagi said the company does not expect a 25 bps increase “to materially impact housing demand,” especially in premium and luxury segments. Landmark Group Chairman Sandeep Chhillar said he does not expect the move “to alter the trajectory of the residential market.” Trehan IRIS Executive Director Aman Trehan was more cautious, saying the immediate impact will be “through borrowing costs and affordability,” particularly for marginal buyers.
Anarock Chairman Anuj Puri, in the quarterly report released before the RBI decision, had said festive-period demand was expected to get support from stable borrowing costs and new launches, while cautioning that buyers “may remain selective because of higher property prices and affordability concerns.” With borrowing costs no longer stable, that second caveat now carries more weight.
Outlook
The RBI has said its stance does not set a predetermined schedule of further hikes, so the path of future rate moves will depend on inflation, crude oil prices and monsoon-linked food prices. For homebuyers, analysts’ advice is to compare lenders’ reset terms, consider part-prepayment, and avoid stretching budgets in a rising-rate cycle. For developers, the festive quarter will show whether end-user demand can absorb both higher prices and higher EMIs, with a large pile of unsold stock waiting in the wings.
Sources: Deccan Herald (7 Oct 2026); Kalkine India (9 Oct 2026); PropNewsTime reporting on Anarock Research Q3 2026 data (2 Oct 2026); NewsVoir/ANI industry reactions via Business Standard (10 Oct 2026). EMI figures are illustrative calculations and not a lender quote.
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate for Realnewsofindia.com
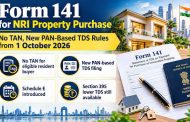
NEW DELHI: Homebuyers purchasing property from Non-Resident Indians (NRIs) are getting a procedural relief this month. Under revised tax-deduction reporting rules effective 1 October 2026, resident individuals and Hindu Undivided Families (HUFs) buying Indian immovable property from a non-resident seller can now deduct and deposit tax using their Permanent Account Number (PAN). They no longer need to obtain a Tax Deduction Account Number (TAN) first.
What has changed
Until now, a resident buyer paying a non-resident seller had to register for a TAN, an extra step that often delayed registrations and closings. The new framework removes that hurdle for individual and HUF buyers. The relief does not extend to companies and firms, which must continue to use a TAN.
The rules also introduce Form 141, which provides consolidated reporting for applicable transactions and replaces multiple earlier forms, as per a summary published by CAclubindia.
TDS rates for NRI sellers
Long-term capital gains (property held for more than 24 months): 12.5%.
Short-term capital gains (held 24 months or less): applicable slab rate, up to 30%.
Surcharge and health and education cess may apply in both cases.
The Rs 50 lakh threshold and the 1% rate apply only where the seller is a resident individual. They do not apply when the seller is a non-resident.
Obligations remain
Buyers must still determine the correct TDS rate, deduct and deposit the tax, and file Form 141. The change simplifies registration, not liability.
Why it matters for the market
NRI buyers and sellers are an important part of demand in markets such as Mumbai, Bengaluru, Hyderabad, Pune and Chennai. Easing compliance for resident purchasers from NRI sellers reduces friction in secondary-market transactions at a time when, per Knight Frank India data reported on Realnewsofindia.com, housing sales across eight major cities were broadly flat at 2,58,238 units in January-September 2026, with the market growing more in value than in volume.
Buyers and sellers are advised to consult a chartered accountant or tax professional and refer to the official notification before closing transactions. This report is for information and is not tax advice.
Sources: CAclubindia: TDS on Purchase of Property, New Reporting Rules From 1st October 2026; Realnewsofindia.com: Housing Sales Hold Steady at 2.58 Lakh Units in Jan-Sep 2026
Written by Ai Powered PMC Akbar Jiwani
Special Correspondent: Realestate for Realnewsofindia.com
Mumbai/New Delhi: India’s residential market ended the July–September 2026 quarter on a cautiously positive note, with housing sales across the top seven cities rising 3% year on year to about 1,00,220 units, according to data released by property consultancy Anarock on 28 September. The units sold were worth roughly Rs 1.55 lakh crore, underlining the continued strength of value-led demand even as unit growth remains modest.
Launches surge, unsold stock builds
New launches rose a sharp 18% year on year to about 1,14,320 units, as developers lined up supply ahead of the festive season. Unsold inventory stood at about 6,30,590 units. Average prices across the seven cities rose 7% year on year to Rs 9,714 per sq ft, though quarter-on-quarter growth was just 1%, suggesting price momentum is cooling.
Southern cities lead, Pune and Chennai lag
Hyderabad recorded a 15% rise in sales and Bengaluru 12%. Pune (down 6%), Chennai (down 10%) and Kolkata (down 4%) saw declines, while Delhi-NCR slipped 1% to 13,765 units.
A different picture from PropEquity
Data analytics firm PropEquity, which tracks nine markets with a different methodology, estimated sales fell about 6% year on year to 1,03,170 units. Its city-wise data showed Navi Mumbai (+12%) and Hyderabad (+11%) growing, while Pune (-16%), Chennai (-17%) and Kolkata (-17%) fell. PropEquity noted its figures were released before quarter-end, so late-September numbers were partly estimated. The divergence reflects differences in cities covered and methodology rather than a contradiction in direction for individual markets such as Hyderabad.
Offices and policy watch
Colliers reported Grade A office leasing across seven cities rose 9% year on year to 18.7 million sq ft in the quarter, with Delhi-NCR more than doubling to 3.3 million sq ft. On the regulatory front, the Supreme Court-appointed committee told the NCLAT that construction of 16 stalled Supertech projects, to be handled by state-run NBCC, is scheduled to begin on 16 January 2027, with tenders due between 1 and 15 October; the projects cover about 50,000 flats, of which roughly 14,000 remain undelivered. Separately, from 1 October 2026, resident individual and HUF buyers of property from non-resident sellers can reportedly report and pay TDS using their PAN instead of a TAN, via Form 141 (per CAclubindia; readers should verify against the official Income Tax Department notification).
Outlook
With the festive season under way and the RBI repo rate reported at 5.25%, industry watchers will track whether strong launches convert into sales. Analysts caution that rising unsold stock and moderating price growth could shape developer pricing strategies in the coming months.
Sources: Anarock and PropEquity data via Realty Hunting roundups (29 Sept 2026) and PropEquity release report; Colliers; CAclubindia.
Written by Ai Powered PMC Akbar Jiwani
Special Correspondent: Realestate for Realnewsofindia.com
New Delhi, 12 October 2026 – India’s residential market is growing in value rather than volume. Housing sales across eight major cities were broadly flat at 2,58,238 units in January–September 2026, according to Knight Frank India data released on 5 October. Buyers are moving towards higher-priced homes, while entry-level demand weakens.
City-wise picture
Mumbai remains the largest market with 72,804 units sold, up 1%. Bengaluru grew fastest among the big markets, rising 5% to 43,140 units. Pune was roughly flat at about 36,402 units. Hyderabad, Ahmedabad, Chennai and Kolkata each grew 2–4%. Together, the seven non-NCR markets rose 2%.
The NCR was the weak spot, with sales down 11% to 35,574 units. Sales in the ₹5–10 crore band there fell 39% to 4,033 units. Gurugram accounts for 57% of the region’s unsold inventory.
Premium homes gain, affordable segment shrinks
Homes priced above ₹1 crore made up 55% of sales, up from 50% a year earlier. The ₹1–2 crore band is the largest segment at 77,087 units, up 6.8%. The ₹2–5 crore band jumped 19.4% to 51,501 units, with Chennai posting 54% growth in this range.
The affordable end is under pressure. Homes priced ₹50 lakh–₹1 crore fell 5.9% to 69,380 units. Homes below ₹50 lakh fell 14% to 47,660 units, and their share of sales dropped to 18%.
Supply and prices
Developers launched 2,79,899 homes in the nine months, up 4%. Q3 launches were 92,549, also up 4%. New supply has exceeded sales for 16 consecutive quarters, pushing the inventory overhang to 6.1 quarters. Prices rose between 3% and 17% across markets.
Knight Frank India chairman Shishir Baijal described the trend as “normalisation rather than a widespread slowdown.” He said income growth, suitable supply and local demand will increasingly determine market performance as the benefits of lower interest rates fade.
Government relief for developers
On 31 July, the Ministry of Housing and Urban Affairs advised state RERAs to extend registration and completion deadlines by four months for projects with deadlines on or after 28 February 2026. The advisory cites supply-chain disruption from the West Asia conflict, which the finance ministry declared a force majeure event on 29 April. It asks RERAs to issue a common order so developers need not file project-by-project applications.
CREDAI president Shekhar Patel called the move “a positive step taken in line with the sector’s demand.”
Also on the regulatory front
From 1 October 2026, resident individual and HUF buyers of property from non-resident sellers can report and pay TDS using their PAN rather than a TAN, with reporting through Form 141. Buyers should verify rates and requirements against official CBDT notifications.
Outlook
With volumes steady, prices rising and the affordable share shrinking, the market is expected to grow in value rather than volume. Affordability for first-time buyers remains the central concern for policymakers and developers.
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
Mumbai/New Delhi: India’s housing market held its ground in the first nine months of 2026. Eight major cities recorded 2,58,238 home sales between January and September, roughly flat on last year, according to Knight Frank India data released on 5 October. The data shows buyers moving steadily towards higher-priced homes, while the entry-level segment weakens.
Mumbai leads, Bengaluru grows fastest among the big markets
The seven markets outside the National Capital Region grew 2% together. Mumbai stayed the largest market with 72,804 sales, up 1%. Bengaluru recorded 43,140 sales, up 5%. Pune was roughly flat at 36,402 units. Hyderabad, Ahmedabad, Chennai and Kolkata each grew between 2% and 4%.
NCR the weak spot
NCR sold 35,574 homes, down 11%. Sales in the ₹5–10 crore band fell 39% to 4,033 units. Gurugram accounts for 57% of the region’s unsold inventory.
Premium homes take a bigger share
Homes priced above ₹1 crore made up 55% of all sales, up from 50% a year ago. The ₹1–2 crore bracket was the largest segment at 77,087 units, up 6.8%. The ₹2–5 crore segment grew 19.4% to 51,501 units, with Chennai posting 54% growth in that range. Sales in the ₹50 lakh–1 crore band fell 5.9% to 69,380 units. Homes below ₹50 lakh fell 14% to 47,660 units, and their share dropped to 18%.
Supply keeps outpacing demand
Developers launched 2,79,899 homes in the nine months, up 4%. Third-quarter launches were 92,549, also up 4%. New supply has exceeded sales for 16 consecutive quarters, and inventory overhang has edged up to 6.1 quarters. Prices rose between 3% and 17% across markets.
Knight Frank India chairman Shishir Baijal described the trend as “normalisation rather than a widespread slowdown.” He said income growth, suitable supply and local demand will increasingly decide how each market performs as the benefits of lower interest rates moderate.
Government relief for developers
Separately, the Ministry of Housing and Urban Affairs on 31 July advised state RERAs to extend registration and completion timelines by four months for projects with deadlines falling on or after 28 February 2026. The advisory cites supply-chain disruption from the West Asia conflict, which the finance ministry declared a force majeure event on 29 April. It also asks RERAs to issue a common order so developers need not file project-wise applications. CREDAI president Shekhar Patel called it “a positive step taken in line with the sector’s demand.”
Outlook: Steady volumes, rising prices and a shrinking affordable share point to a market growing in value rather than volume. Affordability for first-time buyers remains the key concern for policymakers and developers
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate for Realnewsofindia.com
New Delhi/Mumbai, 10 October 2026: India’s housing market has entered the festive season with two developments pulling in different directions. Sales are at a healthy quarterly high, while the Reserve Bank of India (RBI) has raised interest rates for the first time in almost four years.
RBI turns to “calibrated tightening”
On 7 October the RBI’s Monetary Policy Committee raised the repo rate by 25 basis points to 5.5%. This is the first hike since February 2023. The committee also changed its stance from “neutral” to “calibrated tightening”. The rate decision was unanimous, but the stance change passed 4–2.
The central bank cited consumer inflation of 4.8% in August, above its 4% target for a third straight month. It also pointed to volatile crude oil prices linked to renewed US–Iran tensions. It raised its full-year inflation forecast to 5.2% from 5%. It projects GDP growth of 7.1% for the year, after 7.8% growth in the April–June quarter.
What it means for home buyers
More than 68% of floating-rate rupee loans at scheduled commercial banks are linked to external benchmarks that track the repo rate. At private banks the share is above 90%. Floating-rate home loan borrowers can therefore expect a 25 bps rise in rates, which means a higher EMI or a longer loan tenure. Fixed-rate loans will not change immediately but will reprice when their lock-in periods end.
Anuj Puri, Chairman of ANAROCK Group, warned that “even a modest increase in EMIs will result in deferred purchase decisions” among affordable housing buyers. He said commercial real estate is unlikely to see a direct impact, though some new mall projects “could potentially be deferred until there is greater clarity on demand.”
Developers were divided. Ramani Sastri, MD of Sterling Developers, said the hike “would definitely impact housing affordability” and could bring a short-term dip in demand. Rayan Munawer, CEO of Terray Realty, said he does not expect the increase alone to significantly disrupt housing demand. JLL’s Lata Pillai described the move as pre-emptive, aimed at inflation peaks later in the year.
Q3 numbers show a resilient market
The timing matters because the market came into the hike on solid footing. ANAROCK data for July–September 2026 shows the following for the top seven cities:
Sales: about 1,00,220 units, up 3% from 97,080 a year earlier. Sales value was about ₹1.55 lakh crore, up 2%.
New launches: about 1,14,320 units, up 18% from 96,690.
Prices: average residential prices rose 7% year on year. The NCR rose 12% and Bengaluru 8%.
Unsold inventory: about 6.31 lakh units, up 12% from about 5.62 lakh.
City trends varied widely. The Mumbai Metropolitan Region sold about 31,750 units (+5%), Bengaluru 16,670 (+12%) and Hyderabad about 12,970 (+15%, the fastest growth). Pune (−6%), NCR (−1%), Kolkata (−4%) and Chennai (−10%) declined. MMR and Bengaluru together made up 48% of sales.
Hyderabad’s launches more than doubled (+120%) to about 18,950 units. By price band, 34% of new launches were in the ₹80 lakh–₹1.5 crore range and 24% in ₹1.5–2.5 crore. Only 14% were priced below ₹40 lakh. This shows how thin the supply of entry-level homes remains.
The road ahead
Rising inventory, higher prices and costlier loans together mean buyers are likely to stay selective. Analysts say the pace of any further rate action will matter more than this single hike. Developers are expected to lean on festive-season offers and flexible payment plans over the coming weeks. Home buyers are advised to check how their lender’s rate reset works, and to compare fixed and floating options before committing.
By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate for Realnewsofindia.com
MUMBAI/NEW DELHI, 9 October 2026: India’s residential market entered the festive season with modest sales growth and a sharp rise in new supply. Property consultant Anarock’s Q3 2026 report (published 2 October) shows housing sales in the top seven cities rose 3% year-on-year to about 1,00,220 units in July-September, from 97,080 units a year earlier. Sales value rose 2% to about Rs 1.55 lakh crore.
Launches surge. New launches rose 18% to about 1,14,320 units, from 96,690 units in Q3 2025. Mumbai Metropolitan Region (MMR), Pune, Bengaluru and Hyderabad accounted for 81% of new supply. By price band, Rs 80 lakh to Rs 1.5 crore homes made up 34% of launches, Rs 1.5 to 2.5 crore 24%, Rs 40 to 80 lakh 17% and homes below Rs 40 lakh 14%.
Prices and inventory. Average residential prices rose 7% year-on-year, with NCR recording the steepest appreciation at 12%, followed by Bengaluru at 8%. Unsold inventory rose 12% to about 6.31 lakh units, from about 5.62 lakh units a year ago, as supply outpaced absorption.
City-wise picture. Hyderabad was the standout, with sales up 15% to 12,970 units and launches more than doubling (+120%) to 18,950 units. Bengaluru sales rose 12% to 16,670 units. MMR, the largest market, sold 31,750 units (+5%), and together with Bengaluru accounted for 48% of total sales. Pune fell 6% to 15,690 units, NCR dipped 1% to 13,765 units, Kolkata slipped 4% and Chennai declined 10%.
Another view. PropEquity’s report (1 October), covering the top nine cities, recorded 1,03,170 units sold in Q3, down 6% year-on-year and 4% from the previous quarter, with launches down 2% year-on-year and 15% quarter-on-quarter. It showed Hyderabad up 11%, Bengaluru up 1%, Mumbai down 8%, Thane down 11%, Pune down 16% and Chennai down 17%. PropEquity founder and CEO Samir Jasuja noted that absorption fell only 4% despite a sharp drop in supply, keeping the demand-supply balance steady, and linked slower launches to developers’ caution while they manage existing inventory. The two firms cover different city sets and define markets differently, so analysts advise comparing trends rather than totals; both agree on Hyderabad’s strength and weakness in Pune and Chennai.
Outlook. Anarock chairman Anuj Puri said buyers may remain selective because of higher property prices and affordability concerns, but expects the festive period to be supported by stable borrowing costs and new launches. With inventory building up, homebuyers may see more discounts, festive offers and flexible payment plans, while developers are likely to focus on mid-premium and premium segments where demand is steadier.
Sources: Anarock Q3 2026 report via PropNewsTime (2 Oct 2026); PropEquity Q3 2026 report via Grihik (1 Oct 2026). Figures are as reported by the research firms.





Recent Comments