By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate, Realnewsofindia.com
Published: 28 October 2026
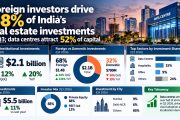
India’s residential real estate market has entered a phase of consolidation. According to Knight Frank India, housing sales across the country’s top eight cities stood at 258,238 units in the first nine months of calendar year 2026 (January to September), broadly flat compared with the same period last year.
The report shows the market plateauing after several years of strong growth, with buyers becoming more selective. Knight Frank India Chairman and Managing Director Shishir Baijal described the trend as normalisation rather than a broad-based slowdown.
City-wise picture
Mumbai remained the largest market with 72,804 units sold, up 1% year-on-year. Bengaluru recorded 43,140 units, a rise of 5%, while Pune stayed largely unchanged at 36,402 units. Hyderabad, Ahmedabad, Chennai and Kolkata each posted growth of 2% to 4%. Taken together, the seven markets outside the National Capital Region grew 2%.
Delhi-NCR was the only major market to decline, with sales falling 11% to 35,574 units. The Rs 5-10 crore segment in NCR was hit hardest, with sales dropping 39% to 4,033 units. Gurugram accounts for 57% of NCR’s unsold inventory.
Buyers move up the ticket-size ladder
Homes priced above Rs 1 crore now make up 55% of all sales, up from 50% a year earlier. The Rs 1-2 crore band is the largest segment at 30% of sales (77,087 units, up 6.8%), while the Rs 2-5 crore band grew fastest at 19.4%. In contrast, affordable and lower-mid segments are under pressure: homes below Rs 50 lakh fell 14% to 47,660 units and their share slipped from 22% to 18%.
Supply continues to outpace demand
New launches totalled 279,899 units in the nine months, up 4%, exceeding sales for the 16th consecutive quarter. In Q3 alone (July-September), sales were 86,767 units (down 1%) against launches of 92,549 units (up 4%). The “quarters to sell” indicator rose to 6.1 from 5.8 a year ago, the highest since Q2 2023, though still well below the 7-11 quarter range seen in 2018-2021. Prices rose in all tracked markets in Q3, with Bengaluru up 11% and most other cities up 3-6%.
Macro and policy backdrop
The demand outlook is supported by a strong economy: GDP grew 7.8% in April-June 2026 and the RBI has held the repo rate at 5.25%. On the regulatory front, the Centre in July advised state RERAs to extend project timelines by four months, offering relief to developers and homebuyers with delayed projects. Analysts say watch-points ahead include NCR’s luxury segment, premium inventory build-up in Bengaluru and Pune, slowing absorption at the lower end, and limited room for further rate support due to inflation.
The takeaway: India’s housing story is shifting from volume to value. With sales steady, prices firm and buyers trading up, the market appears to be maturing, though rising inventory and weak affordable-housing demand call for policy and developer attention.