By AI Powered PMC Akbar Jiwani, Special Correspondent: Real Estate for Realnewsofindia.com
India’s residential real estate market is entering the festive season on firm footing, with fresh industry data showing that home prices across the country’s top eight cities have stayed above the ₹10,000 per square foot mark for a second consecutive quarter, even as sales volumes cooled slightly from a year earlier. Combined with a steady interest-rate environment and GST relief on key construction inputs, the sector is being described by analysts as “maturing, not weakening.”
WHAT THE DATA SHOWS
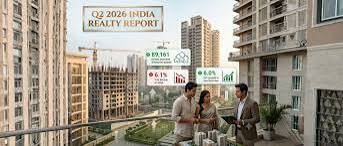
According to the Real Insight Residential report for Q2 2026 released by PropTiger.com (part of listed real estate technology firm Aurum PropTech Limited), the top eight cities together recorded 91,729 housing units sold against 89,161 new launches during the quarter.
Sales fell 4.4% quarter-on-quarter and were down 6.1% compared with 97,674 units sold in the same quarter last year.
New launches, however, rose 6.0% year-on-year from 84,138 units.
The sales-weighted average price across the eight cities rose 1.0% quarter-on-quarter to ₹10,153 per square foot, holding above the ₹10,000 threshold for the second straight quarter.
City-wise, the Mumbai Metropolitan Region remained the largest market by both volume and value, with 24,112 units sold and prices up 20.4% year-on-year to ₹15,422 per square foot. Bengaluru posted the steepest annual price rise among the eight cities at 26.0%, even as sales there slipped 9.2%. Pune crossed the ₹8,000 per square foot mark for the first time, up 13.7% year-on-year, while Ahmedabad remained the most affordable large market at ₹5,295 per square foot but logged the sharpest sequential price gain, up 7.0% quarter-on-quarter. Kolkata led sequential sales growth nationally with a 22.0% quarter-on-quarter rise, which the report attributes to a post-election demand recovery, and Chennai recorded a 36.0% year-on-year jump in sales even as new supply fell 43.3%. Hyderabad and Delhi-NCR were comparatively stable, with Hyderabad launches up 21.6% year-on-year.
WHY PRICES ARE RISING DESPITE SOFTER SALES
PropTiger.com chief executive Prakash Tejwani said the numbers point to a market that is stabilising rather than slowing down. “Q2 2026 confirms India’s residential market is maturing, not weakening,” he said, noting that prices have held above ₹10,000 per square foot for two straight quarters even as buyers turn more selective. He pointed to Kolkata and Chennai as showing “genuine demand-led recovery,” while Bengaluru and Pune “continue to command pricing power despite tech-sector caution.” Sanjeevini Group chairman and founder Umesh Gowda H A said Bengaluru’s market “continues to remain resilient despite a broader moderation in housing activity across India,” describing the softer sales as “a more measured pace of absorption rather than a weakening of the market.”
POLICY TAILWINDS: STABLE RATES AND GST RELIEF
The pricing resilience comes against a backdrop of supportive government and central bank policy. The Reserve Bank of India has held its repo rate steady at 5.25%, keeping home loan borrowing costs predictable for buyers. Separately, the GST Council’s rate rationalisation earlier this year cut the tax on cement from 28% to 18% and on marble and granite from 12% to 5%, a change industry estimates suggest could offset construction costs by roughly 2–3%, offering developers some cushion against rising input and land prices even as it has yet to meaningfully lower end prices for buyers.
WHAT TO WATCH NEXT
With disciplined new supply and inventory levels still under control, developers are heading into the festive quarter — traditionally India’s strongest home-buying season around Navratri and Diwali — with pricing power intact. Analysts say affordability will remain the key variable to watch through the rest of 2026: whether launch volumes convert into fresh sales once festive-season promotions and offers begin, and whether the GST-driven cost relief eventually filters through to more competitively priced units for first-time buyers in India’s price-sensitive mid-income segment.