By Ai Powered PMC Akbar Jiwani, Special Correspondent: Realestate for Realnewsofindia.com
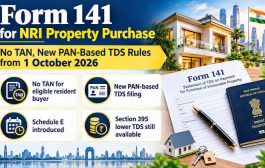
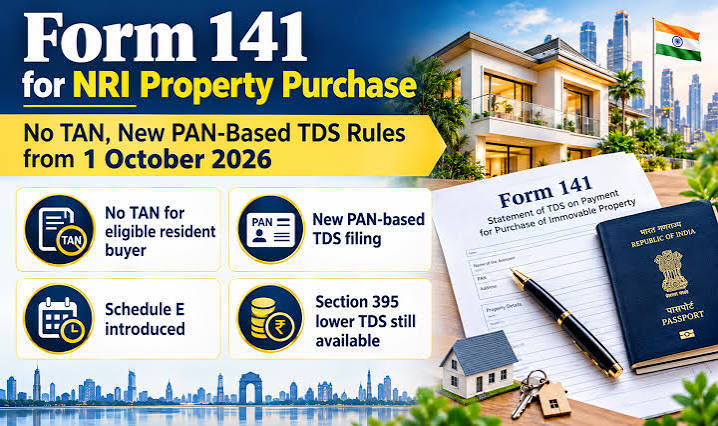
NEW DELHI: Homebuyers purchasing property from Non-Resident Indians (NRIs) are getting a procedural relief this month. Under revised tax-deduction reporting rules effective 1 October 2026, resident individuals and Hindu Undivided Families (HUFs) buying Indian immovable property from a non-resident seller can now deduct and deposit tax using their Permanent Account Number (PAN). They no longer need to obtain a Tax Deduction Account Number (TAN) first.
What has changed
Until now, a resident buyer paying a non-resident seller had to register for a TAN, an extra step that often delayed registrations and closings. The new framework removes that hurdle for individual and HUF buyers. The relief does not extend to companies and firms, which must continue to use a TAN.
The rules also introduce Form 141, which provides consolidated reporting for applicable transactions and replaces multiple earlier forms, as per a summary published by CAclubindia.
TDS rates for NRI sellers
Long-term capital gains (property held for more than 24 months): 12.5%.
Short-term capital gains (held 24 months or less): applicable slab rate, up to 30%.
Surcharge and health and education cess may apply in both cases.
The Rs 50 lakh threshold and the 1% rate apply only where the seller is a resident individual. They do not apply when the seller is a non-resident.
Obligations remain
Buyers must still determine the correct TDS rate, deduct and deposit the tax, and file Form 141. The change simplifies registration, not liability.
Why it matters for the market
NRI buyers and sellers are an important part of demand in markets such as Mumbai, Bengaluru, Hyderabad, Pune and Chennai. Easing compliance for resident purchasers from NRI sellers reduces friction in secondary-market transactions at a time when, per Knight Frank India data reported on Realnewsofindia.com, housing sales across eight major cities were broadly flat at 2,58,238 units in January-September 2026, with the market growing more in value than in volume.
Buyers and sellers are advised to consult a chartered accountant or tax professional and refer to the official notification before closing transactions. This report is for information and is not tax advice.
Sources: CAclubindia: TDS on Purchase of Property, New Reporting Rules From 1st October 2026; Realnewsofindia.com: Housing Sales Hold Steady at 2.58 Lakh Units in Jan-Sep 2026