By Ai Powered PMC Akbar Jiwani, Special Correspondent: Real Estate, for Realnewsofindia.com
Mumbai/New Delhi: India’s housing market held its ground in the first nine months of 2026. Eight major cities recorded 2,58,238 home sales between January and September, roughly flat on last year, according to Knight Frank India data released on 5 October. The data shows buyers moving steadily towards higher-priced homes, while the entry-level segment weakens.
Mumbai leads, Bengaluru grows fastest among the big markets
The seven markets outside the National Capital Region grew 2% together. Mumbai stayed the largest market with 72,804 sales, up 1%. Bengaluru recorded 43,140 sales, up 5%. Pune was roughly flat at 36,402 units. Hyderabad, Ahmedabad, Chennai and Kolkata each grew between 2% and 4%.
NCR the weak spot
NCR sold 35,574 homes, down 11%. Sales in the ₹5–10 crore band fell 39% to 4,033 units. Gurugram accounts for 57% of the region’s unsold inventory.
Premium homes take a bigger share
Homes priced above ₹1 crore made up 55% of all sales, up from 50% a year ago. The ₹1–2 crore bracket was the largest segment at 77,087 units, up 6.8%. The ₹2–5 crore segment grew 19.4% to 51,501 units, with Chennai posting 54% growth in that range. Sales in the ₹50 lakh–1 crore band fell 5.9% to 69,380 units. Homes below ₹50 lakh fell 14% to 47,660 units, and their share dropped to 18%.
Supply keeps outpacing demand
Developers launched 2,79,899 homes in the nine months, up 4%. Third-quarter launches were 92,549, also up 4%. New supply has exceeded sales for 16 consecutive quarters, and inventory overhang has edged up to 6.1 quarters. Prices rose between 3% and 17% across markets.
Knight Frank India chairman Shishir Baijal described the trend as “normalisation rather than a widespread slowdown.” He said income growth, suitable supply and local demand will increasingly decide how each market performs as the benefits of lower interest rates moderate.
Government relief for developers
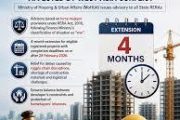
Separately, the Ministry of Housing and Urban Affairs on 31 July advised state RERAs to extend registration and completion timelines by four months for projects with deadlines falling on or after 28 February 2026. The advisory cites supply-chain disruption from the West Asia conflict, which the finance ministry declared a force majeure event on 29 April. It also asks RERAs to issue a common order so developers need not file project-wise applications. CREDAI president Shekhar Patel called it “a positive step taken in line with the sector’s demand.”
Outlook: Steady volumes, rising prices and a shrinking affordable share point to a market growing in value rather than volume. Affordability for first-time buyers remains the key concern for policymakers and developers